

When people talk about building a trading strategy, in most cases there’s a player behind it who got disappointed by randomness and realized his results were randomness all along. The statistics of the last twenty years say the same thing. ESMA, the EU’s markets regulator, looked at retail client accounts at CFD brokers: 74 to 89% of them lose money. A study of Brazilian day traders is even harsher: of those who kept trading for more than 300 days, 97% lost money, and only 0.5% earned more than a bank teller’s starting salary.
Is it about knowledge? I don’t think so.
According to S&P Global, 85.59% of active large-cap US funds lagged the S&P 500 over 10 years, 89.93% over 15 years and 92.89% over 20 years. And the winners barely repeat: apart from small-cap funds, not one fund from the top quartile in 2021 stayed there through the end of 2025.
There are dozens of studies like these, across different countries and continents, and the conclusion is almost always the same: people are very likely to lose money trading. The sooner that sinks in, the better. Then there’s a choice: take another path, or go deeper into this one with your eyes open.
So the question is: how do you survive in the market? Not with a secret strategy, but with an edge over the people you trade against, plus the ability to last until that edge can be proven. And the main question isn’t “how do I become a profitable trader”. It’s “why should I, specifically, beat whoever’s on the other side of the trade”.
If there’s no concrete answer to that, the data says a loss is the most likely outcome.
In this piece I’ll show how to build a small but profitable strategy, and even though research says that after publication a strategy’s returns drop by about 58% simply because market participants “devour” it, that doesn’t scare me: as early as December 6, 2026 the market open effect will most likely wash out more, and you can already see it. On top of that, it’s one of the simplest in my trading.
Let’s get started.
Where the question comes from
Anyone trading index futures intraday has OVN High and OVN Low (the overnight high and low) on the chart by default. In Market Profile and Volume Profile they're the starting point: that's where you measure from to see where the market went after the night. And there's an observation everybody knows: after the open, price gets pulled toward the closer of the two.
The observation’s correct, but pull has nothing to do with it.
Say there’s a dot between two walls, stepping left or right at random. One wall’s a step away, the other’s four. It’ll bump into the near one 80% of the time, no pull at all, just because it’s closer. That’s the gambler’s ruin problem, and the answer’s been known for a long time.
So my baseline is a random walk with no drift, a market where past prices don’t tell you future ones. I only call something an effect if it goes beyond that.
Data and definitions
Data and sample
CME one-minute bars for ES from June 2, 2017 to October 13, 2026, New York time. I checked the ES minute bars against five-minute bars from the same source: highs and lows matched in every interval.
Instruments (main session in New York time, tick, tick value, commission in ticks per round turn, days in sample):
ES (E-mini S&P 500): 9:30-16:00, 0.25, $12.50, 0.36, 2,295 days.
NQ (E-mini Nasdaq-100): 9:30-16:00, 0.25, $5.00, 0.90, 2,295.
YM (E-mini Dow): 9:30-16:00, 1, $5.00, 0.90, 2,295.
RTY (E-mini Russell 2000): 9:30-16:00, 0.1, $5.00, 0.90, 2,264.
The overnight runs from 18:00 on the previous trading day to 9:29. OVN High and OVN Low are the high and low of the minute bars in that window, and the open is the open of the 9:30 bar. I cut the regular session (9:30-16:00) into 13 half-hour periods, from A (9:30-10:00) to M (15:30-16:00). A touch counts in the first minute where the bar’s high reached OVN High (or its low reached OVN Low).
Out of 2,415 ES trading days I threw out 83 shortened sessions and 37 roll days, when the contract changed during the overnight or the session. Another 33 days fell out because “which boundary is closer” doesn’t make sense on them: on 19 the open landed right on a boundary, on 8 both were the same distance away, and on 6 the open was outside the range altogether. Those six were all in March 2020, when CME’s 5% limit kicked in overnight and the level was set by an exchange rule rather than the market. That leaves 2,262 days: 238 to 245 a year, 137 in 2017 (the data starts in June) and 190 in 2026 (through October 13). On 1,307 of them OVN High was closer, on 955 OVN Low.
Costs: commission of about $4.50 per round turn per contract (0.36 ticks on ES), slippage of 0.5 ticks on the market entry, 1 tick on the stop and 0.5 ticks on the time exit. The target fills on a limit, no slippage. If target and stop hit in the same minute, I count half a win and half a loss.
Skew and the null model
The main variable here is the skew: where inside the range the open sits. d_near and d_far are the distances in ticks to the near and far boundary:
An 85/15 skew means r = 0.15: 15% of the range to the near boundary, 85% to the far one. Skew doesn’t depend on the price level. And ES went from about 2,400 to 7,900 points over the period, so 40 ticks in 2017 and 40 ticks in 2026 are completely different distances.
The null model. If price wanders randomly with no drift, the chance of reaching the near boundary before the far one is
In that market, betting that “the near one comes first” makes zero on average. The model has no time limit, so I only compare it with days where at least one boundary was touched (2,151 days).
The stats here are simple. Confidence intervals (CI) are Wilson intervals: the range where the true share lies with 95% confidence. Fit to the model is a chi-square test over 10 skew bins, which compares how many days there were with how many the model expected. AUC shows how well a distance measure predicts the outcome: 0.5 is a coin flip, 1.0 is a perfect forecast.
73% is geometry
Frequency and skew
The near boundary is touched first on 73.1% of days (95% confidence interval, CI: 71.2-74.9%; 1,653 days). The far one comes first on 22.0% (20.4-23.8%; 498 days), neither on 4.9% (4.1-5.9%; 111 days). Over the whole session the near one gets touched on 77.6% of days (75.9-79.3%; 1,756 days), the far one on 39.4% (37.4-41.4%; 891 days). The gap of 103 days (4.6%) is the days when price hit the far one first.
From there, skew decides everything. With the open almost on the boundary (95/5 or stronger), the near one comes first on 97.5% of days. Near the middle of the range it’s only 44% (χ² = 245.3 with 9 degrees of freedom, p < 10⁻⁴⁷).
Breakdown by skew over all 2,262 days (days; near first with 95% CI; far first; near touched in period A; near touched during the session; median d_near in ticks):
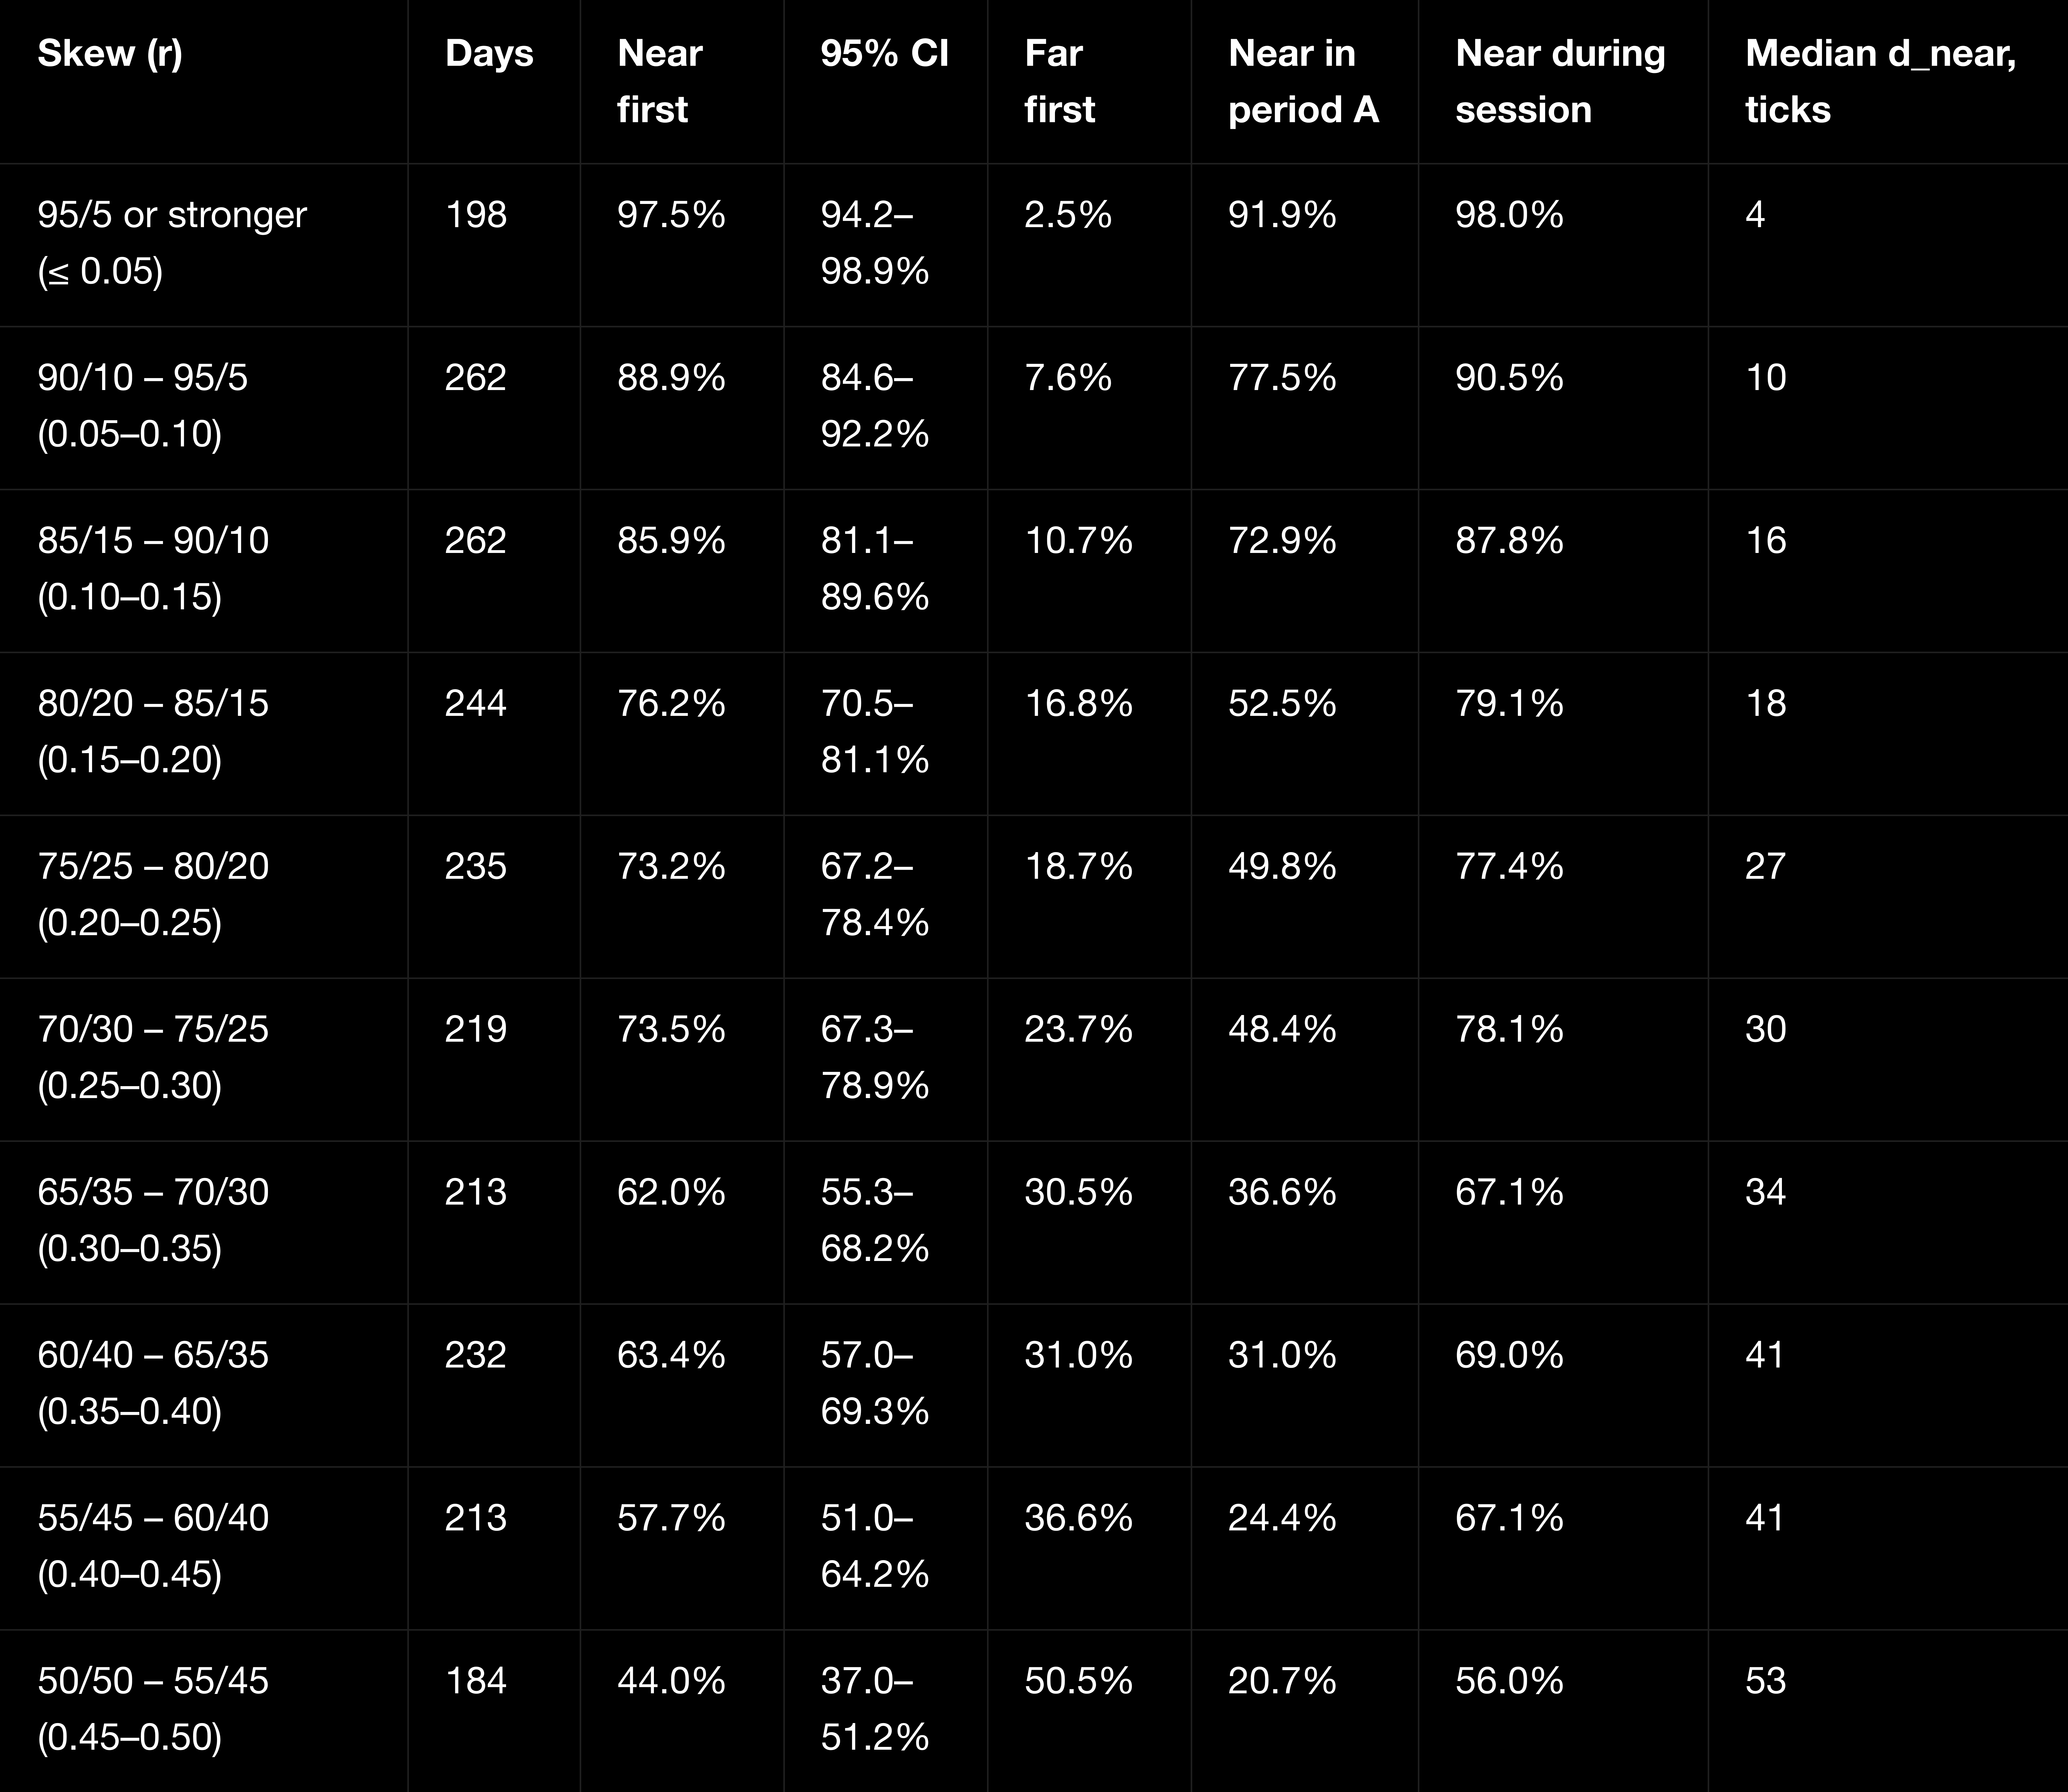
Skew predicts the outcome a lot better than distance in ticks or as a percent of price: AUC 0.730 versus 0.638 and 0.643.
Against the model
The observed probabilities match the 1 − r model in all ten bins: 76.8% against 75.9% (z-statistic 1.06, p = 0.29). Goodness of fit: χ² = 7.96 with 10 degrees of freedom, p = 0.63. Pure chance produces a gap this big or bigger in 63% of samples. The model expected 1,633 days with the near boundary first; there were 1,653. A gap of 20 days out of 2,151. The biggest deviation is near the middle of the range, 46.6% versus 52.7%, and it’s within noise too.
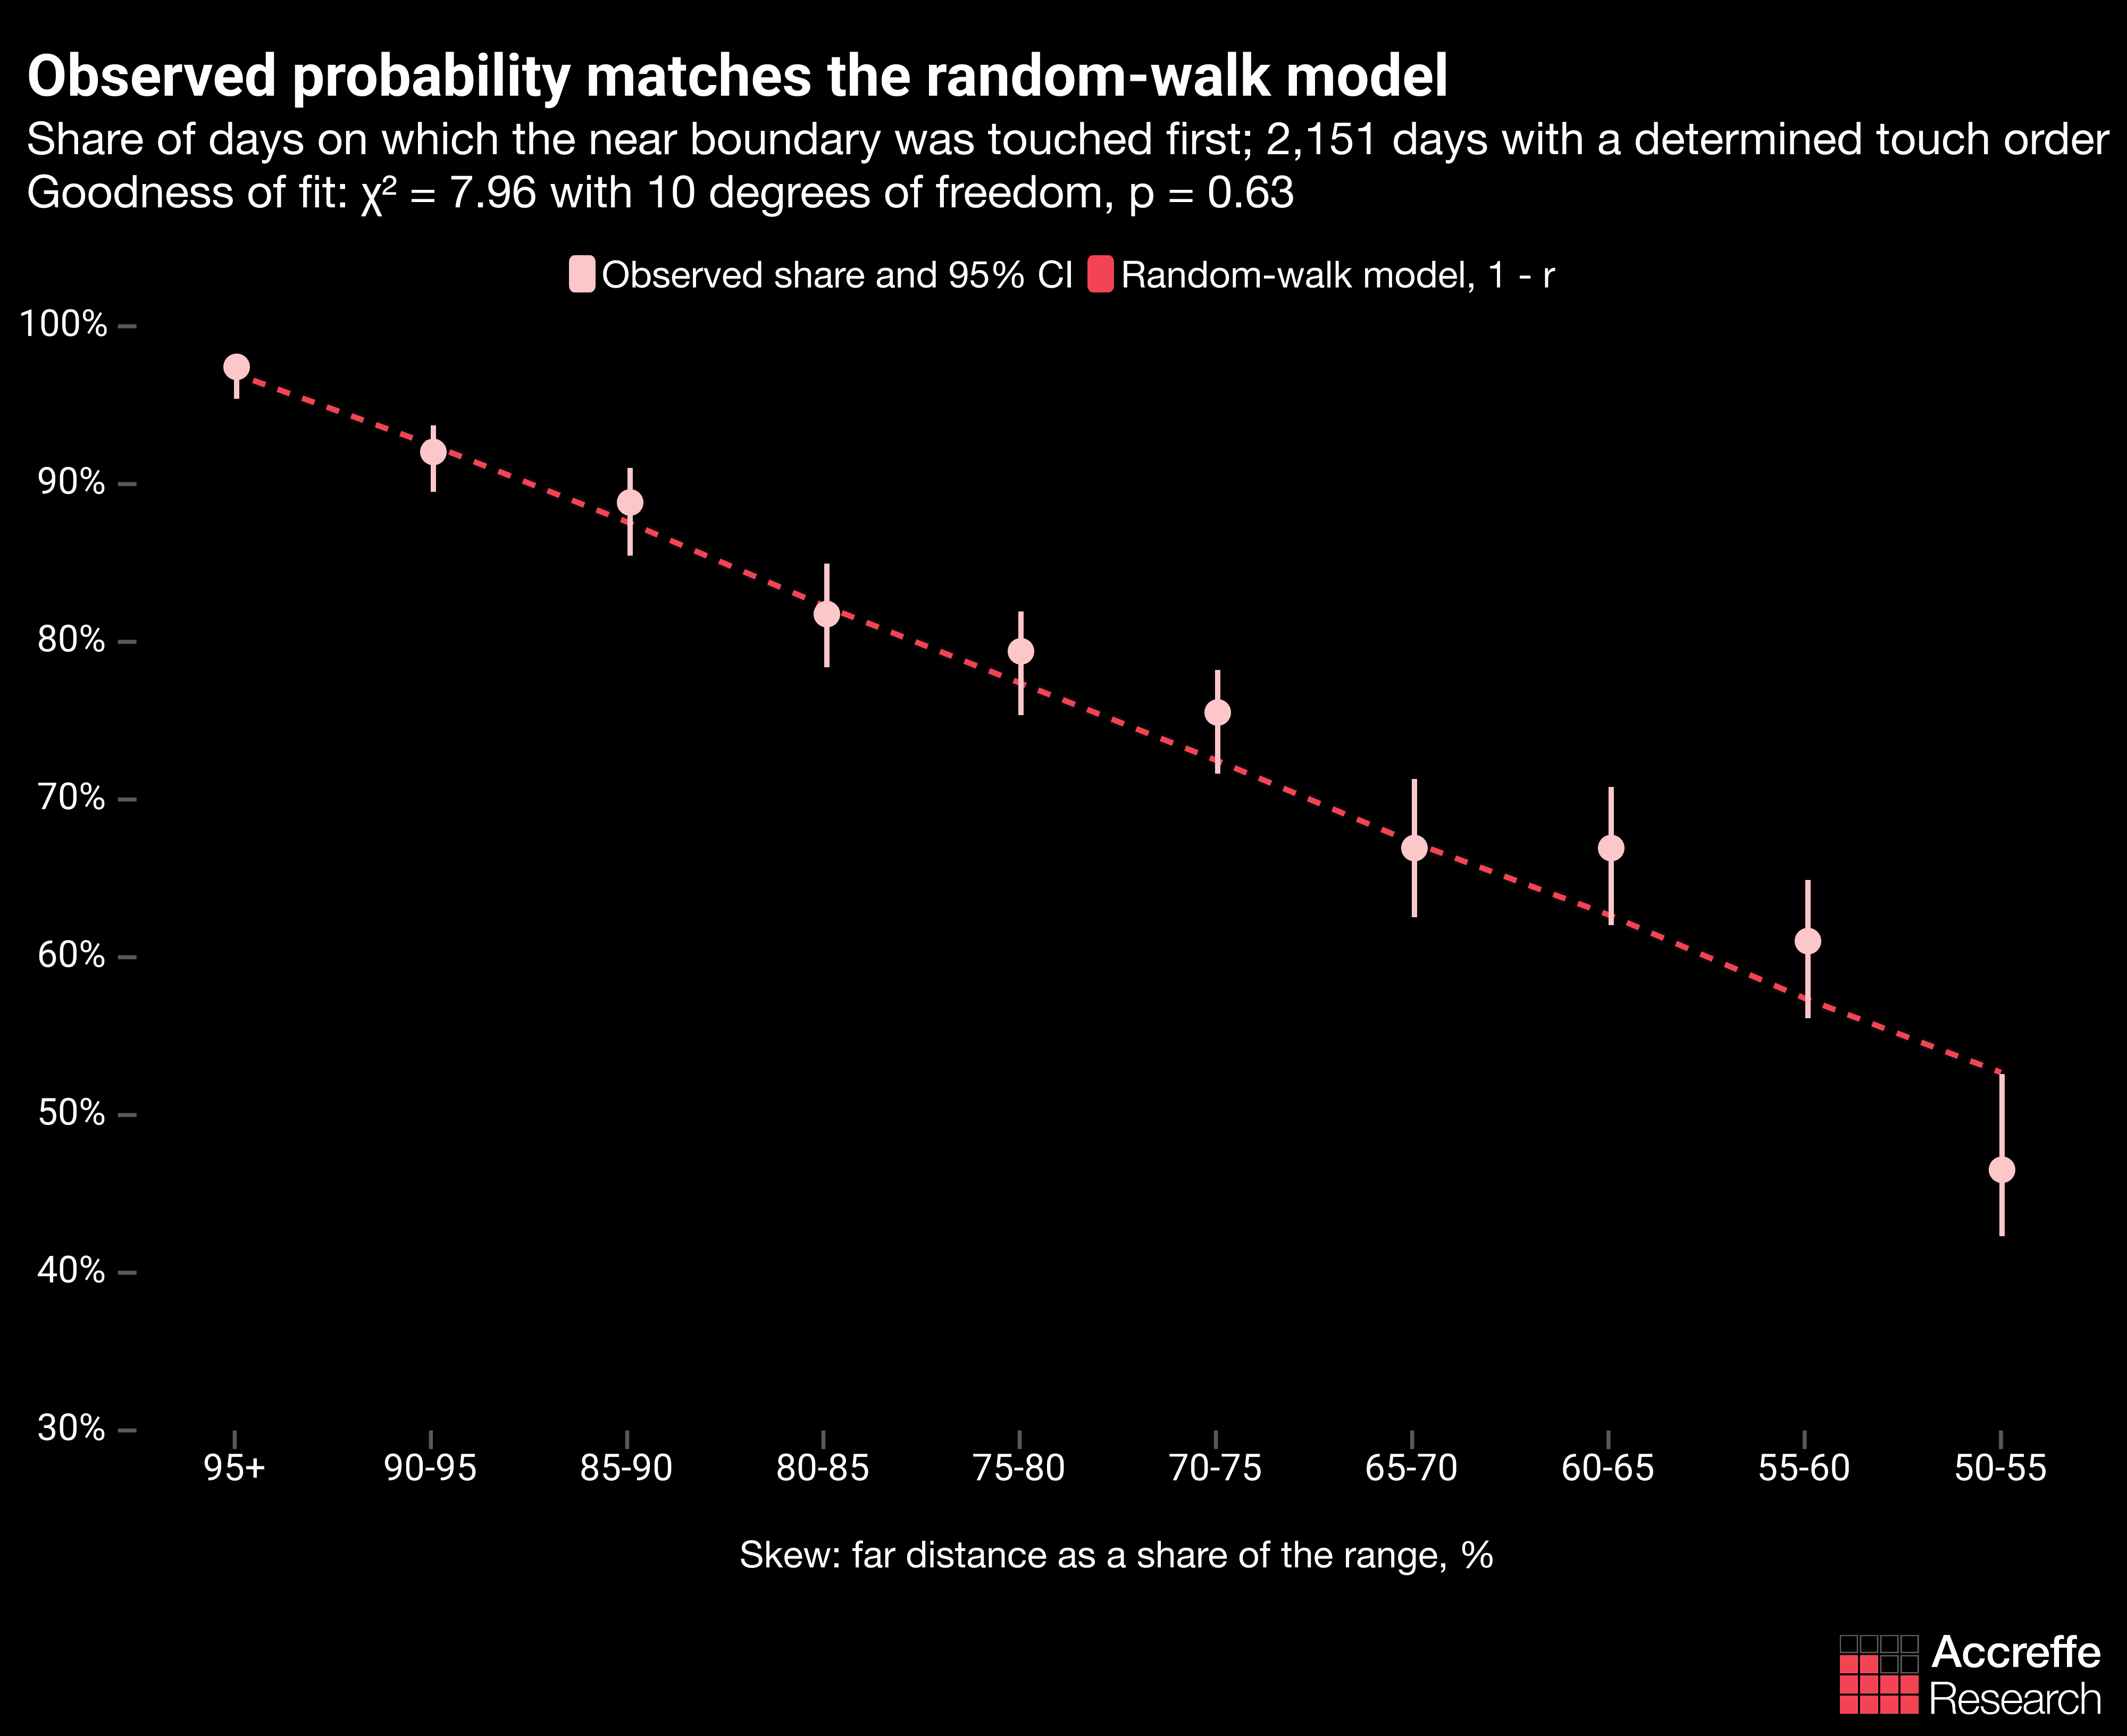
The dependence on skew is fully explained by range geometry, and there's no level pulling price in, not in this data.
Robustness
The result holds up over time. In 2017-2021 and 2022-2026 the near-first share is 76.8% and 76.9%, with the model at 75.7% and 76.1%. Skew AUC is 0.747 and 0.714. At OVN High the share is 77.7%, at OVN Low 75.7%, but even that gap comes almost entirely from opens near the high sitting closer on average: after comparing with the model, 0.5 and 1.6 percentage points (pp) are left.
By year, the session touch rate moves between 71.4% (2020) and 82.8% (2022), and the differences are moderately significant (p = 0.04). In 2020, days with no touch rose to 11.8%, and the median distance to the near boundary went up to 35 ticks against 24 for the full sample. The median overnight range grew from 34 ticks in 2017 to 163 in 2025. As a percent of price it sits around 0.6% most of the time: 0.33% in 2017 and about 1.1% in the volatile years 2020 and 2022. Any tick threshold drifts over time because of this, which is why I work in skew throughout.
When touches happen
In the first half hour (period A) the near boundary has already been touched on 51.6% of days (95% CI: 49.5-53.6%), which is 66% of all touches in the session. After 11:00, each half hour adds about one pp.
The chart’s cumulative. On days without a touch yet, the chance drops fast: with no touch by 10:00, it happens before the close 53.8% of the time; by 11:00, 35.5%; by 12:30, 23.6%.
After an empty first half hour, skew barely matters anymore: 57.3% for a skew of 80/20 or stronger against 51.3% for weaker than 70/30. Strong skew pays off mostly in the first half hour.
The symmetric trade: you win often and make nothing
That gives a trading conclusion right away. The trade goes from the open toward the near boundary: target on the near one, stop on the far one, and if nothing’s touched by 16:00, exit at the close. All 2,262 days, same costs.
Expected Value (EV) in ticks before costs (± standard error) and after:
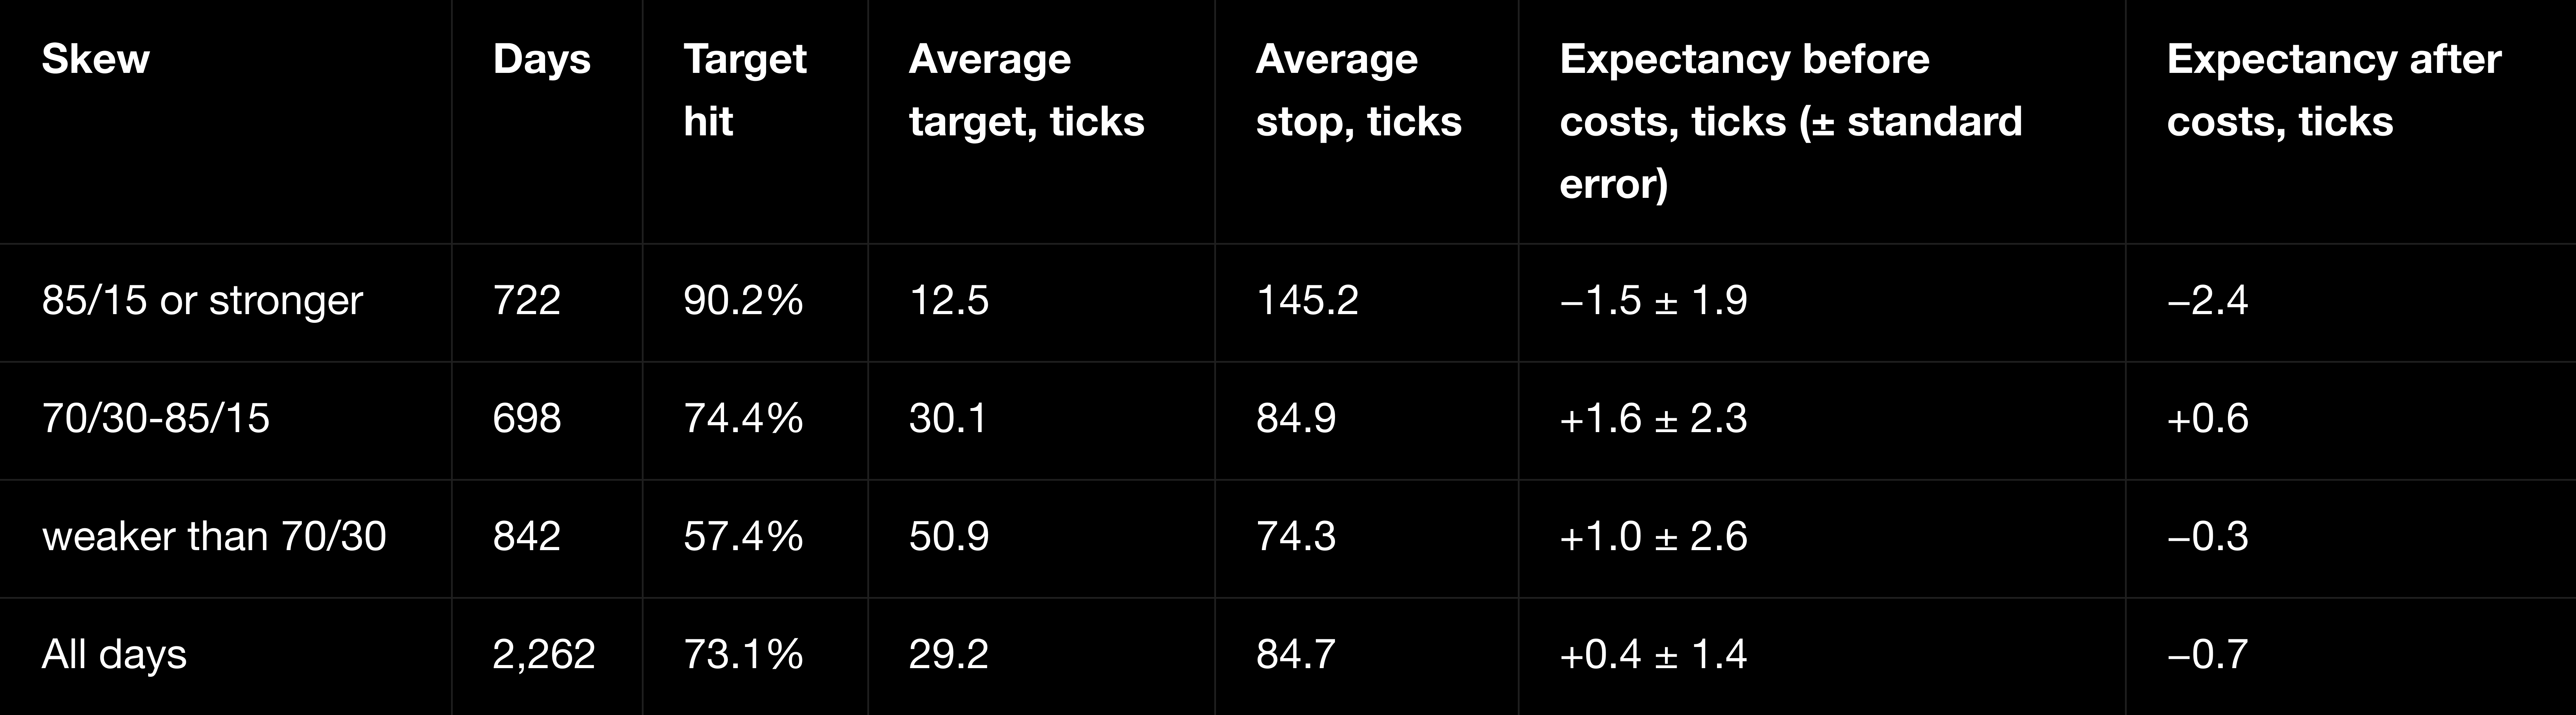
In the strong zone the target gets hit on 90% of days, but the average stop is 11.6 times the average target. Across all days it’s +0.4 ticks before costs, statistically zero (z = 0.3), and −0.7 ticks after.
That doesn’t make the levels useless. You can only make money on them asymmetrically: the target beyond the level, and a stop wide enough to survive the pullback of the first few minutes. What’s needed is an asymmetric trade that barely makes it through the conditions.
The asymmetric trade at the high
The rule
If the open is inside the range, closer to OVN High and 8-17% of the range below it, I buy ES at the market at 9:30. P is the distance from the open to OVN High in ticks, Q the distance to OVN Low, r = P / (P + Q).
Entry conditions, all at once:
OVN Low < open < OVN High.
P < Q: the high is closer than the low.
0.08 < r ≤ 0.17, a skew from 83/17 to 92/8.
P is at least 4 ticks.
Not a shortened session and not a roll day.
The target sits at open + 1.5 × P, half a P above OVN High (median on ES 23 ticks). The stop sits at open − 2 × P (median 31 ticks). If nothing fires by 16:00, I’m out at the market. Median time in the trade is 9 minutes.
Risk per trade is a fixed share of the current account, 1% by default. I measure results in R, units of risk: +0.151R means a trade makes 15% of the amount at risk on average.
The 1.5 ticks are slippage on the entry and the stop, so a full stop comes to roughly −1R. The account is recalculated after every trade, and I don’t model rounding to whole contracts.
How I got there
The rule didn’t show up all at once. I got to it in five steps on the same ES data, keeping the best variant at each one, which means I was fitting. Numbers are after costs, 1% risk, $100,000 start.
Symmetric trade toward the near boundary: target P, stop P, all days. 2,145 trades, win rate 48.0%, −0.079R, the account fell to $16,623. I dropped symmetry.
Asymmetric stop: target P, stop 2 × P, ten r bins of 5%, from 104 to 255 trades each. Only the 10-15% bin was positive, so I kept looking around it.
Zone bounds: 5-15%, 8-15%, 8-17%, 10-17% and 10-20%, from 334 to 503 trades. Results from −0.011R (10-20%) to +0.080R (10-17%), with 8-17% at +0.058R. I kept the 8-17% zone, a skew from 83/17 to 92/8.
Target of 1, 1.2, 1.5 and 2 × P with a 2 × P stop, 434 trades. That gave +0.058, +0.073, +0.094 and +0.067R. I kept the 1.5 × P target.
Side: long toward OVN High (270 trades) or short toward OVN Low (164). Long +0.151R, short −0.001R. I kept the long only.
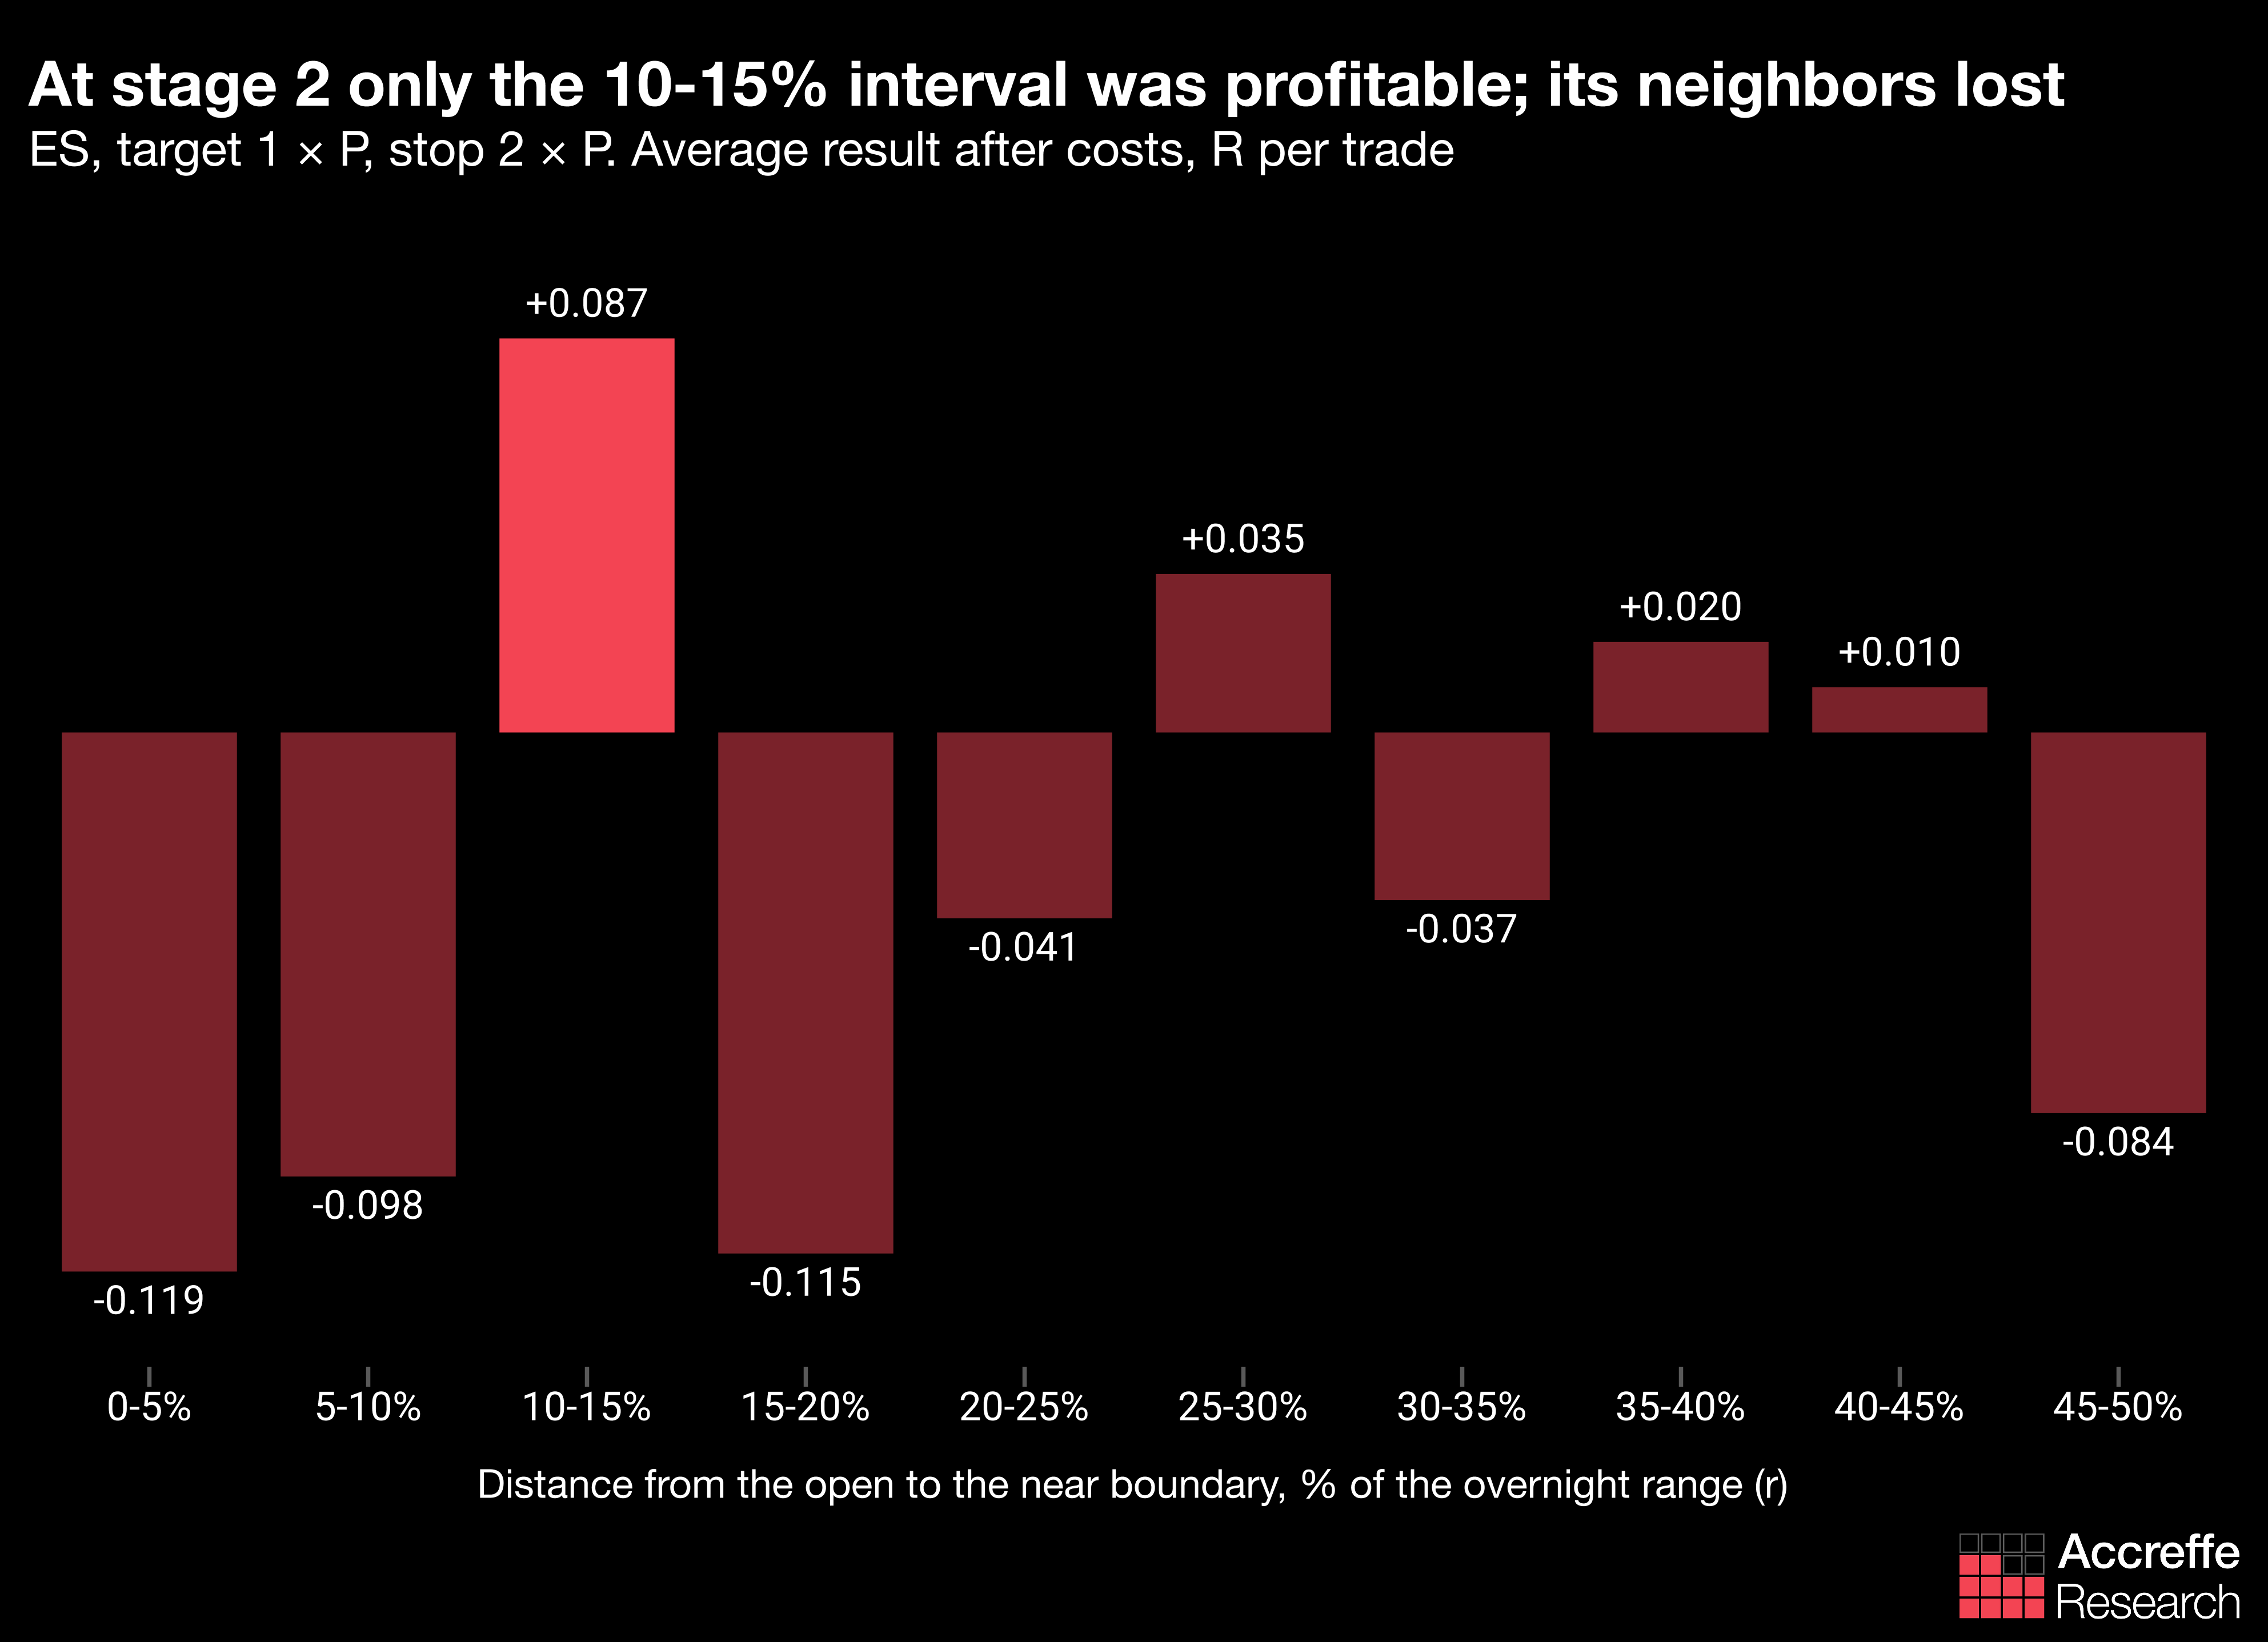
The narrow peak at 10-15% is suspicious. A real pattern usually changes smoothly, and a lone positive bin among negative neighbors often turns out to be noise: with 10 bins and a standard error of about 0.04R, one bin with t around 2 shows up by chance alone. Shifting the bounds bears this out: with a 5-15% or 10-20% zone the gain is gone. I threw out the short after looking at the result. That’s selection too.
To account for all this searching honestly later, I put it into a grid of 14,820 variants: lower r bound from 0.02 to 0.20 in steps of 0.01, zone width from 0.03 to 0.15, side (long, short or both), stop of 1, 1.5, 2, 2.5 or 3 × P and target of 1, 1.2, 1.5 or 2 × P. Everything I looked at along the way is in there. The 4-tick minimum on P isn’t in the grid: I set it up front to cut tiny distances and didn’t tune it.
Results
Metrics
270 trades, +0.151R each on average, 68.9% winners. With this win/loss ratio you’d break even at about 60%. The target hit on 68.9% of trades, the stop on 30.7%, the 16:00 exit on 0.4%. Dollar figures are at 1% risk of the current account and a $100,000 start.
Per trade:
270 trades, about 29 a year, all long. Win rate 68.9%.
Average win +0.68R (+27.1 ticks), average loss −1.01R (−41.6 ticks). Payoff ratio, the average win over the average loss, is 0.67.
Profit factor 1.48.
Expected Value per trade (EV) +0.151R. That’s about +5.7 ticks, or +$71 per ES contract, or +0.15% of the account at 1% risk.
EV t-statistic 3.18. System Quality Number (SQN) 1.9.
95% bootstrap CI of EV from +0.058 to +0.244R.
Skewness of trade results −0.81, kurtosis 1.67.
Longest streaks: 10 wins and 4 losses.
Median time in trade 9 minutes.
For the account at 1% risk of the current balance and a $100,000 start:
Total return +49.1%, CAGR 4.4% a year.
Maximum drawdown −5.2%. The longest drawdown is 484 days and still running since June 16, 2025.
Calmar (CAGR over max drawdown) 0.83.
Annual volatility 3.8%.
Sharpe 1.15 and Sortino 2.11 (monthly, annualized).
Ulcer index 1.8.
Positive months 61%, or 64% among months with trades. Best month +2.9%, worst −2.3%.
In its raw form SQN is the same as the t-statistic and grows with the number of trades, so Tharp caps it at 100 trades to compare systems that trade at different rates. Volatility, Sharpe and Sortino come from monthly returns over all 113 months, including 6 empty ones. The Ulcer index is the root-mean-square drawdown depth: it picks up not just how deep the account goes but how long it sits under its high. The negative skewness comes from how the trade’s built: frequent small wins and less frequent full stops.
The account over time
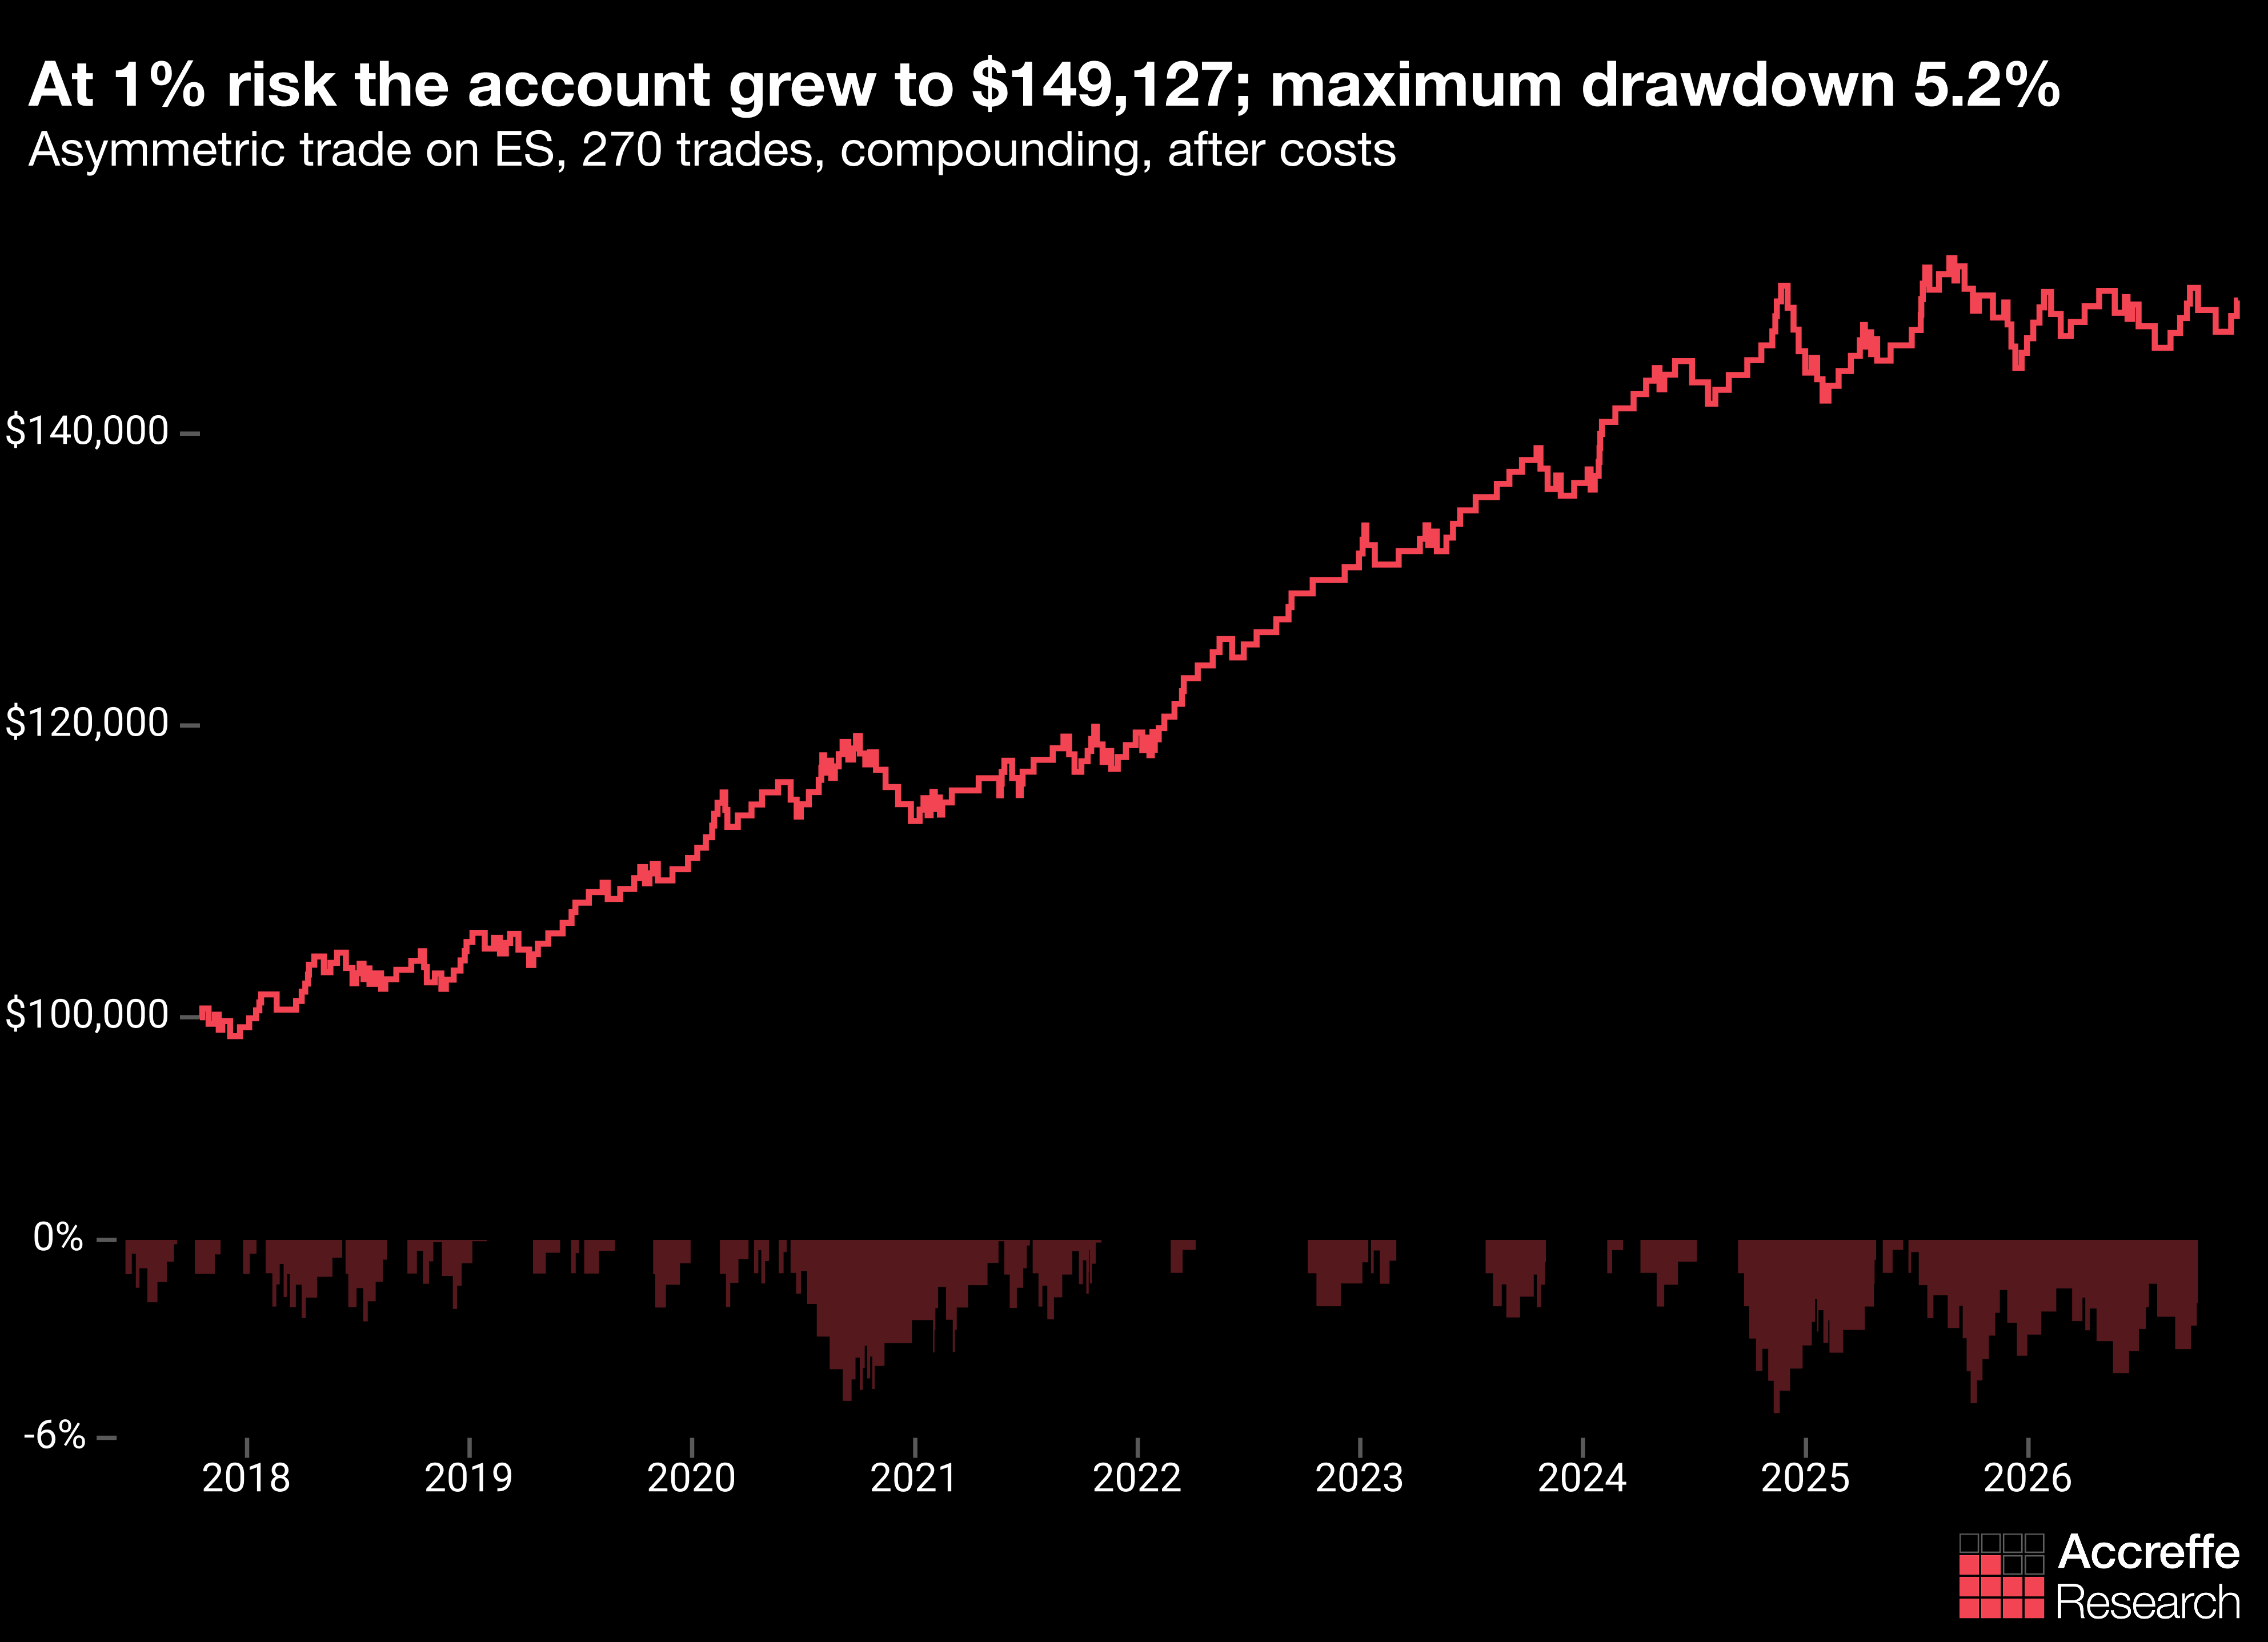
The account hasn’t made a new high since June 2025. The drawdown’s shallow but the longest in the whole history, about 16 months. The last three years made about 1.7% a year against 4.4% on average for the period.
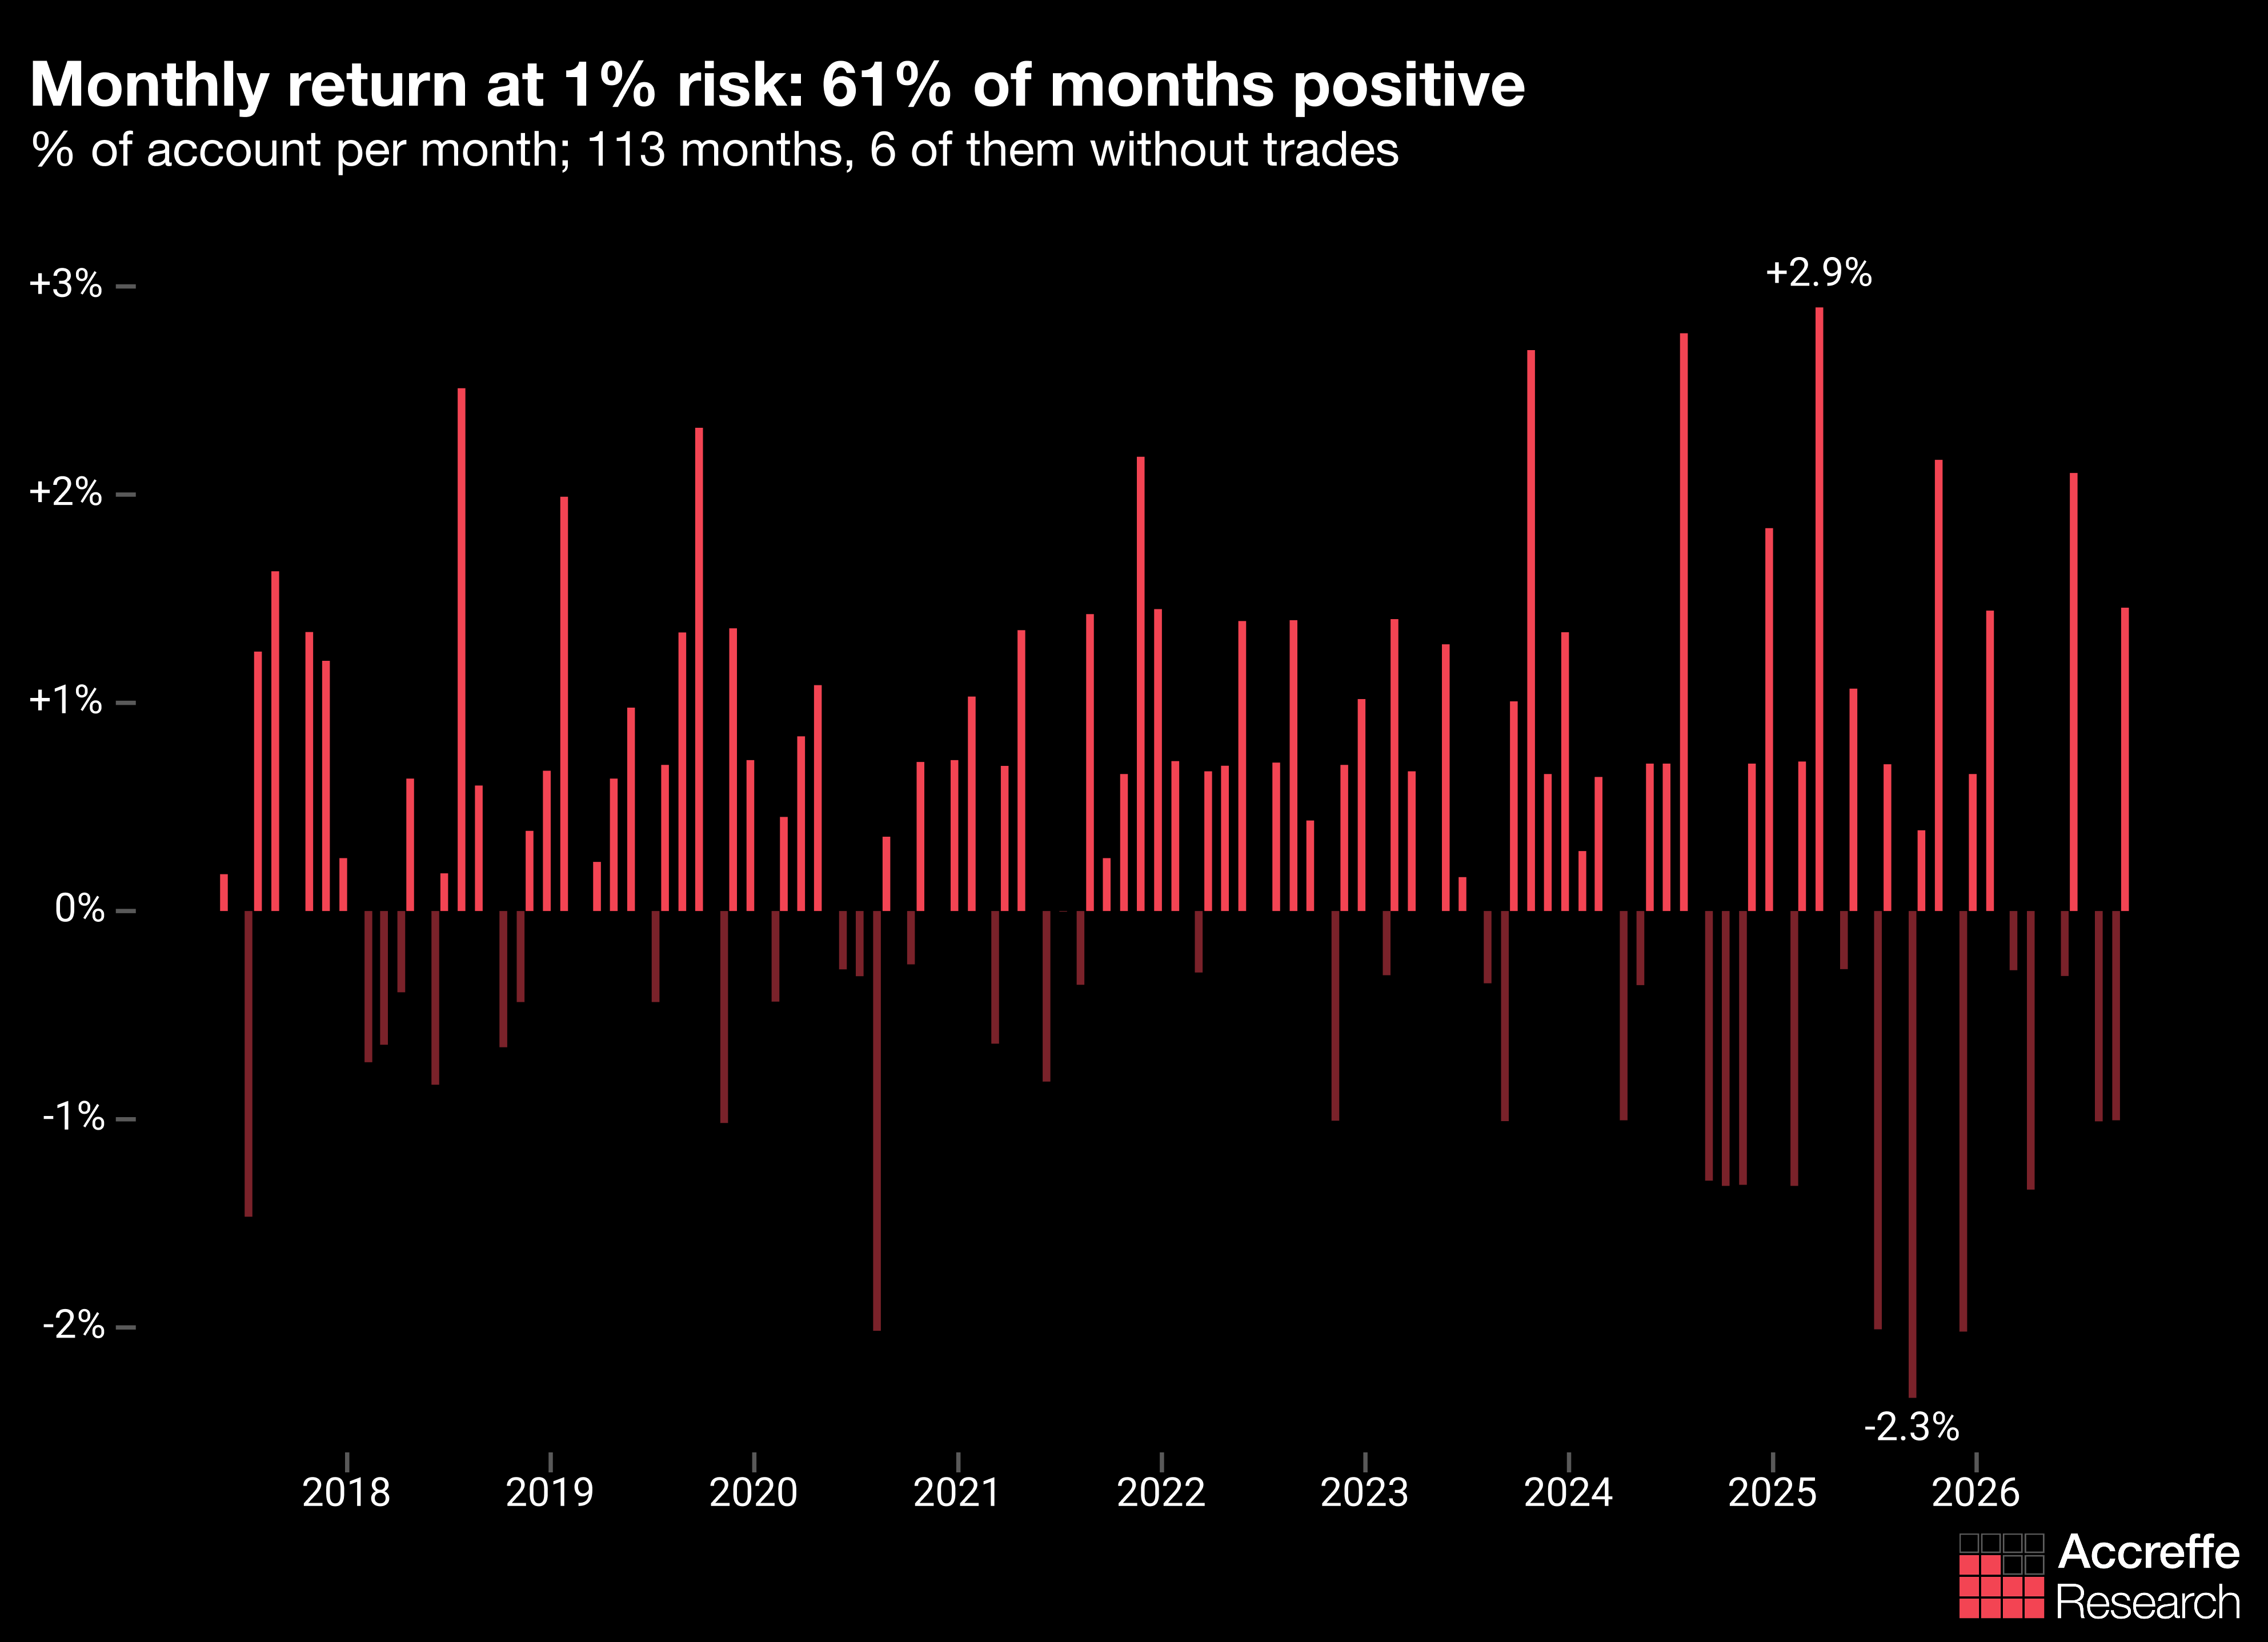
By year (trades, win rate, return, drawdown within the year, year-end balance):
2017, from June: 18 trades, 78%, +4.2%, −1.9%, $104,165.
2018: 35, 63%, +0.8%, −2.5%, $105,043.
2019: 26, 81%, +9.1%, −2.0%, $114,585.
2020: 35, 60%, +0.8%, −4.9%, $115,545.
2021: 37, 70%, +6.7%, −2.4%, $123,238.
2022: 17, 82%, +7.1%, −2.0%, $131,946.
2023: 26, 77%, +7.4%, −2.3%, $141,732.
2024: 25, 64%, +1.8%, −5.2%, $144,293.
2025: 34, 62%, +1.7%, −5.0%, $146,691.
2026, to October 14: 17, 65%, +1.7%, −2.6%, $149,127.
EV in R doesn’t depend on risk, so return and drawdown grow almost in proportion with it. At 2% per trade the account would have reached $218,606 (CAGR 8.7%, drawdown −10.3%), at 3% $314,985 (13.0% and −15.1%). Calmar stays around 0.85.
How much of this is the search
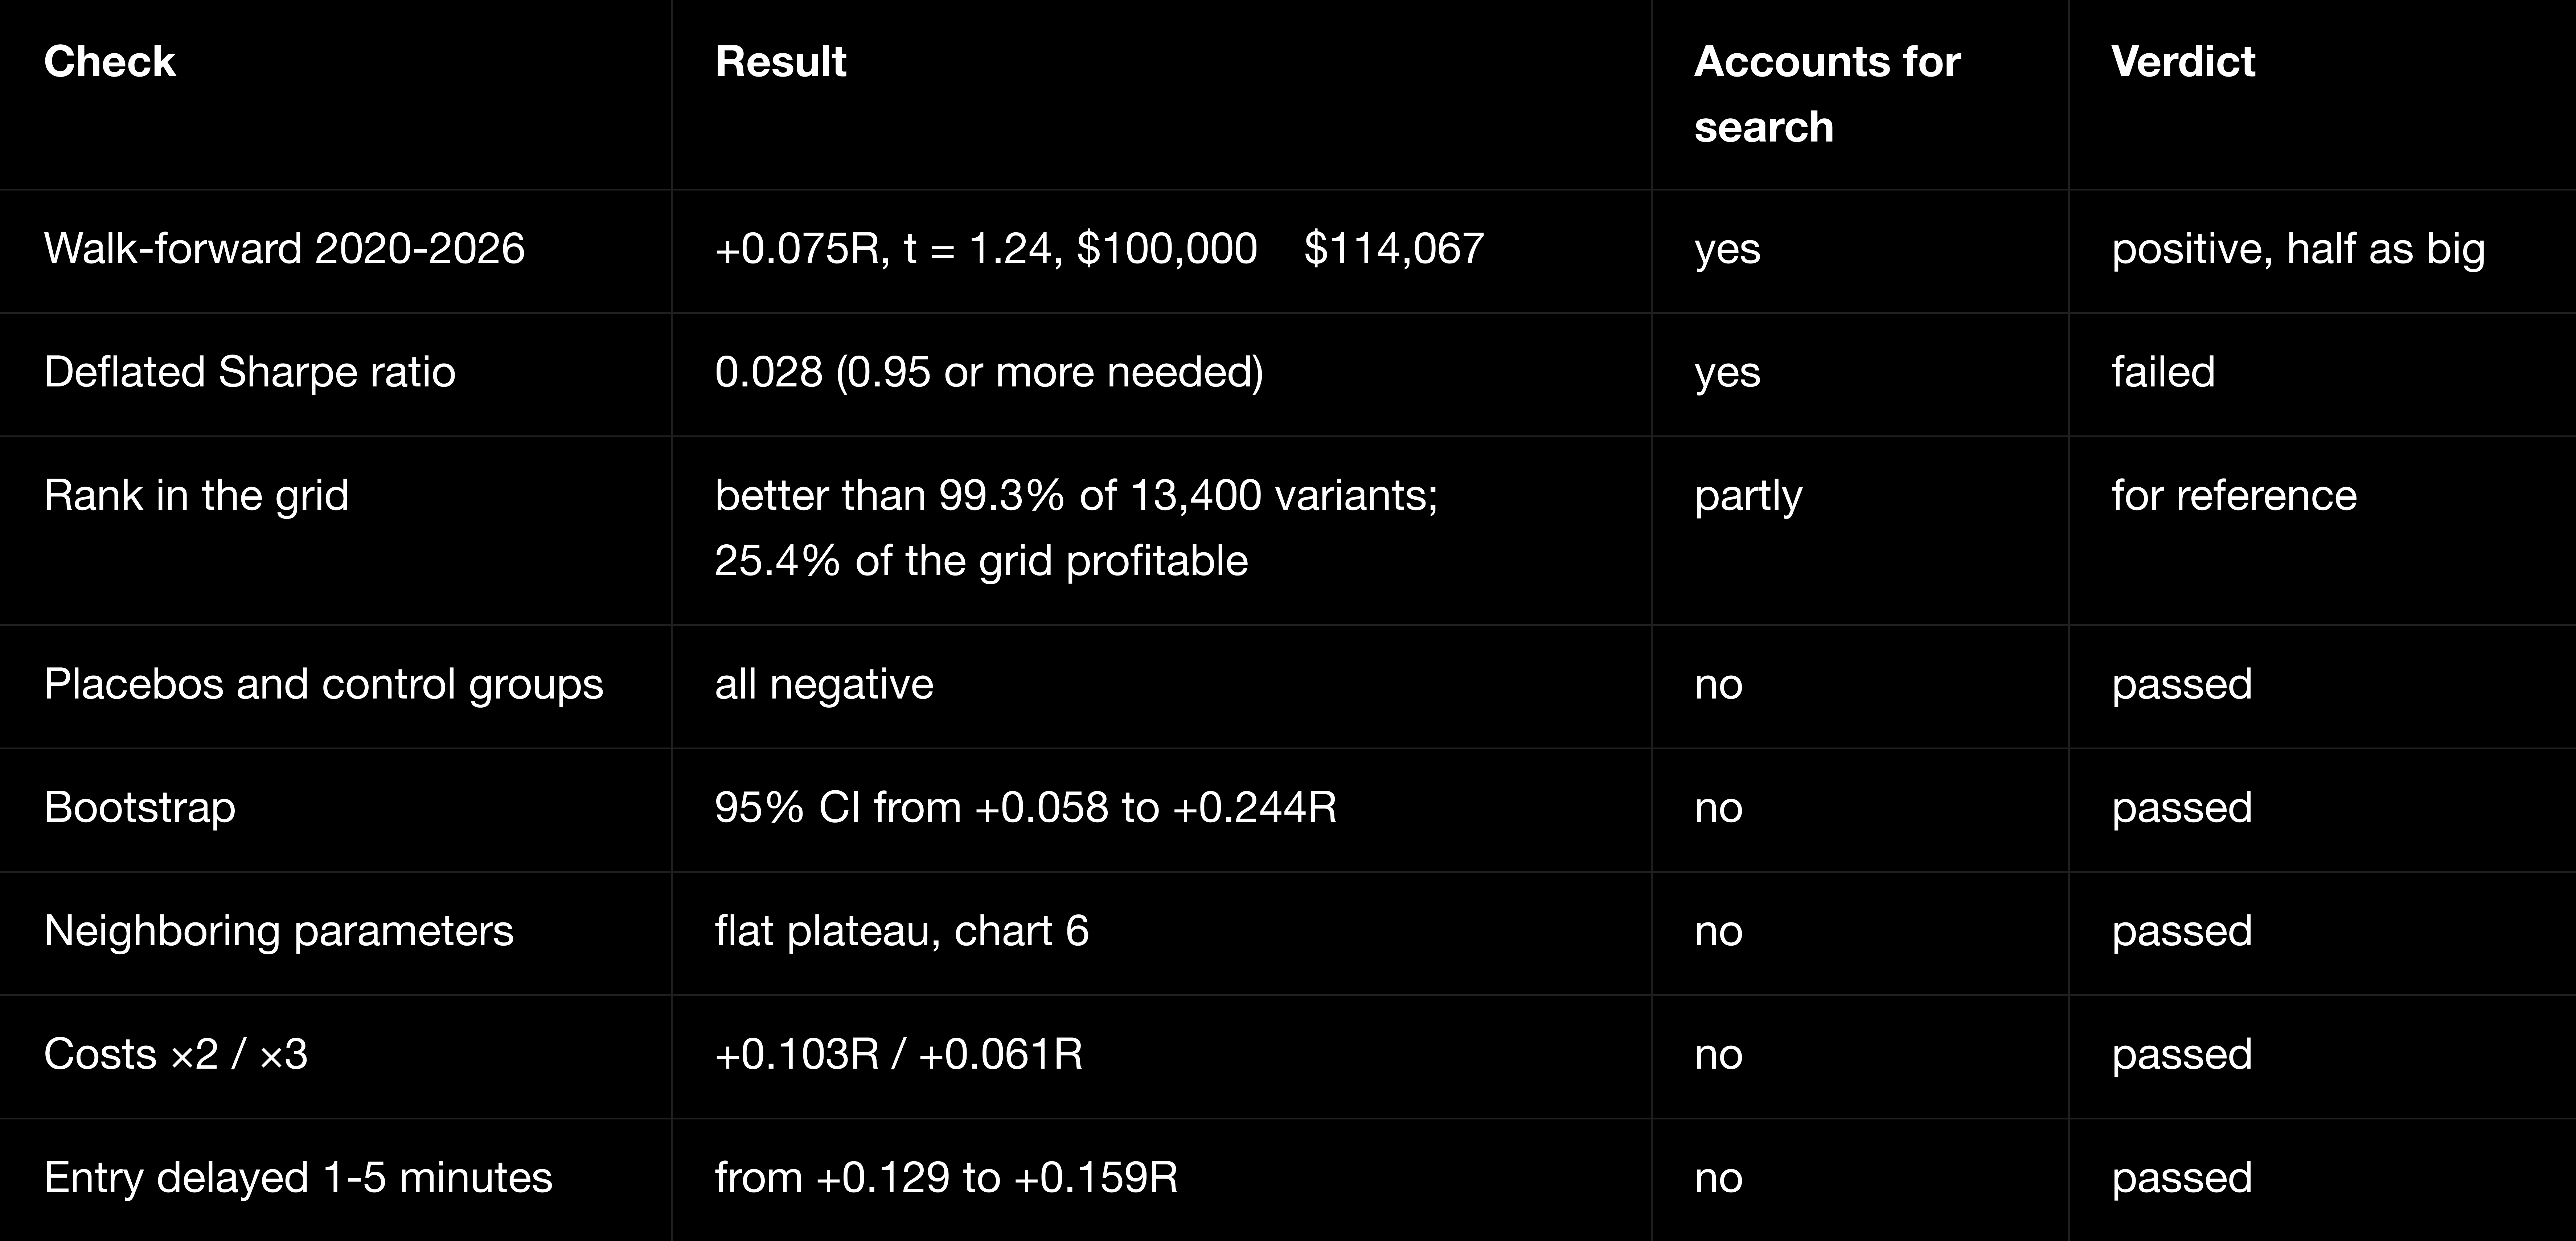
There are two kinds of checks here. Some account for how many variants I tried and answer how much selection inflated the result. Others test the rule that’s already been picked. You have to pass the second kind, but it’s not enough: those checks don’t know there were 14,819 other rules before this one.
Walk-forward
Walk-forward is trading without knowing the future. At the start of each year from 2020 to 2026, I took the grid variant with the best t-statistic over all prior years (at least 60 trades) and traded it for the whole next year. A year’s trades don’t affect which rule gets chosen for that year.
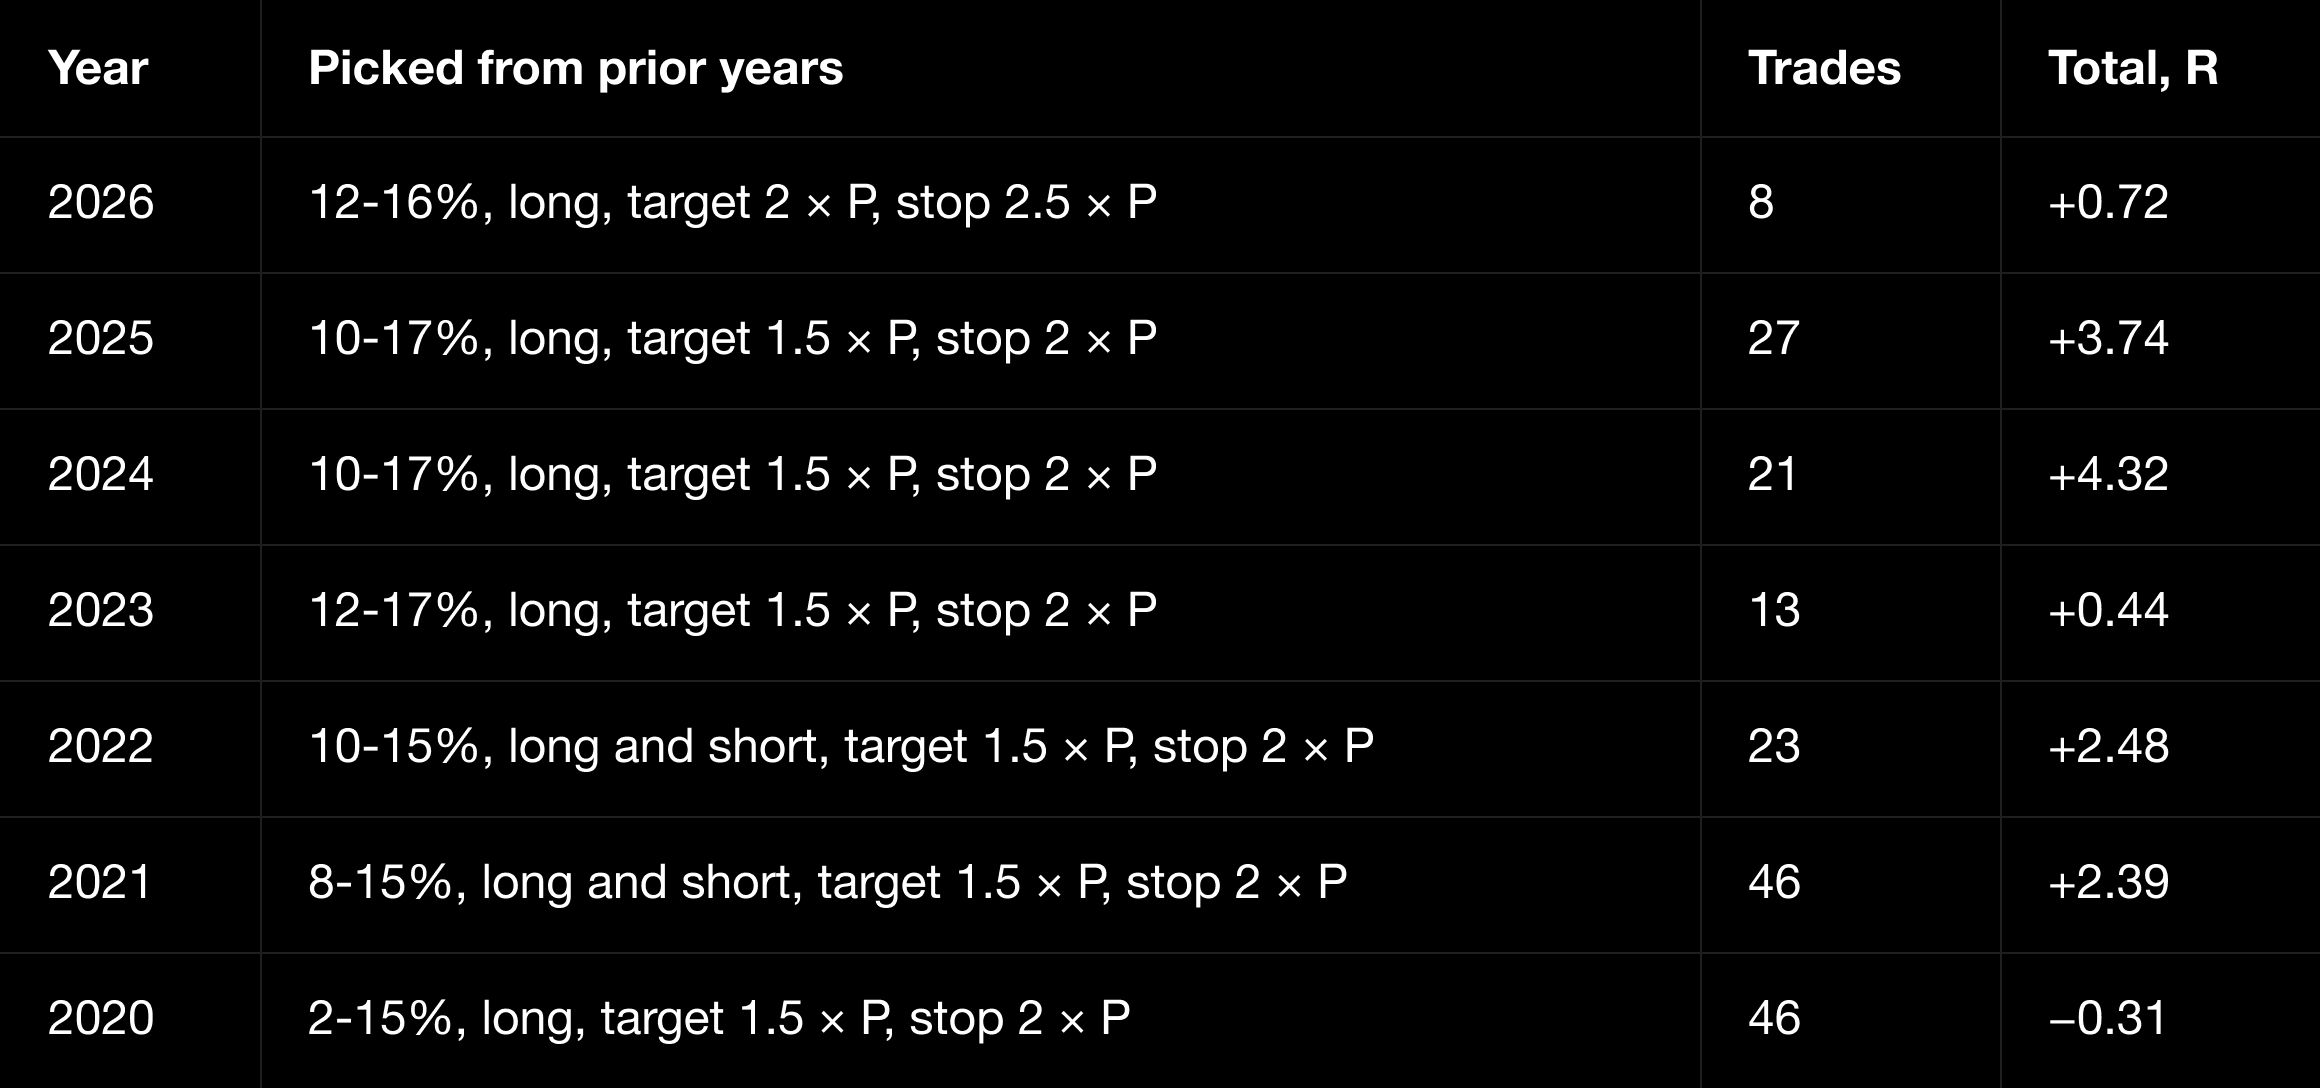
The result: 184 trades, +0.075R on average, $114,067 from $100,000, about 2% a year. The final rule over the same years made 191 trades at +0.141R and $130,145. If you fix the 8-17% zone and the long side up front and only pick target and stop each year, you get +0.095R and $119,051. About half the backtest is choosing after the fact.
Still, from 2021 on the procedure lands on a zone around 10-17%, a 1.5 × P target and a 2 × P stop by itself.
Deflated Sharpe ratio
Try a thousand random strategies and the best one will show a decent Sharpe out of pure luck. Bailey and López de Prado came up with the deflated Sharpe ratio (DSR) for exactly this trap. It answers one question: what’s the probability that the strategy’s true Sharpe is above the best Sharpe you’d get purely by chance among N tried variants? Significance needs 0.95 or higher. The formula’s for anyone curious; the number at the end is enough for everyone else.
Φ is the standard normal distribution function, Φ⁻¹ its inverse, T the number of trades, γ₃ and γ₄ skewness and kurtosis, γ the Euler constant. Sharpe per trade is 0.194, T = 270, skewness −0.81, kurtosis 1.67. Across the 13,400 grid variants with at least 100 trades, the spread of Sharpe is σ_SR = 0.081. That puts the bar at SR₀ = 0.320 and gives DSR = 0.028.
Without the search adjustment (the probabilistic Sharpe ratio, PSR) it would be 0.998. Grid variants are heavily linked to each other, so the real number of independent tries is below 13,400. But even at N = 100, DSR is only 0.43. Once you account for the search, significance isn’t proven.
Checks of the chosen rule
The placebos say the opposite, but about something else: the reverse trade on the same days, the same long on all other days and the long outside the 8-17% zone all lose money.
A bootstrap rebuilds the same set of trades at random, here 20,000 times. It gives a 95% CI for EV from +0.058 to +0.244R and a 0.08% chance that the mean is zero or below. Resampling whole years gives less than 0.01%. Shuffling trade order (5,000 times) gives a median max drawdown of −6.5% and −10.1% in the worst 5% of cases at 1% risk. A random year of 29 trades loses money 16.1% of the time, median +4.4%. All of these treat the rule as fixed in advance, so they’re optimistic.
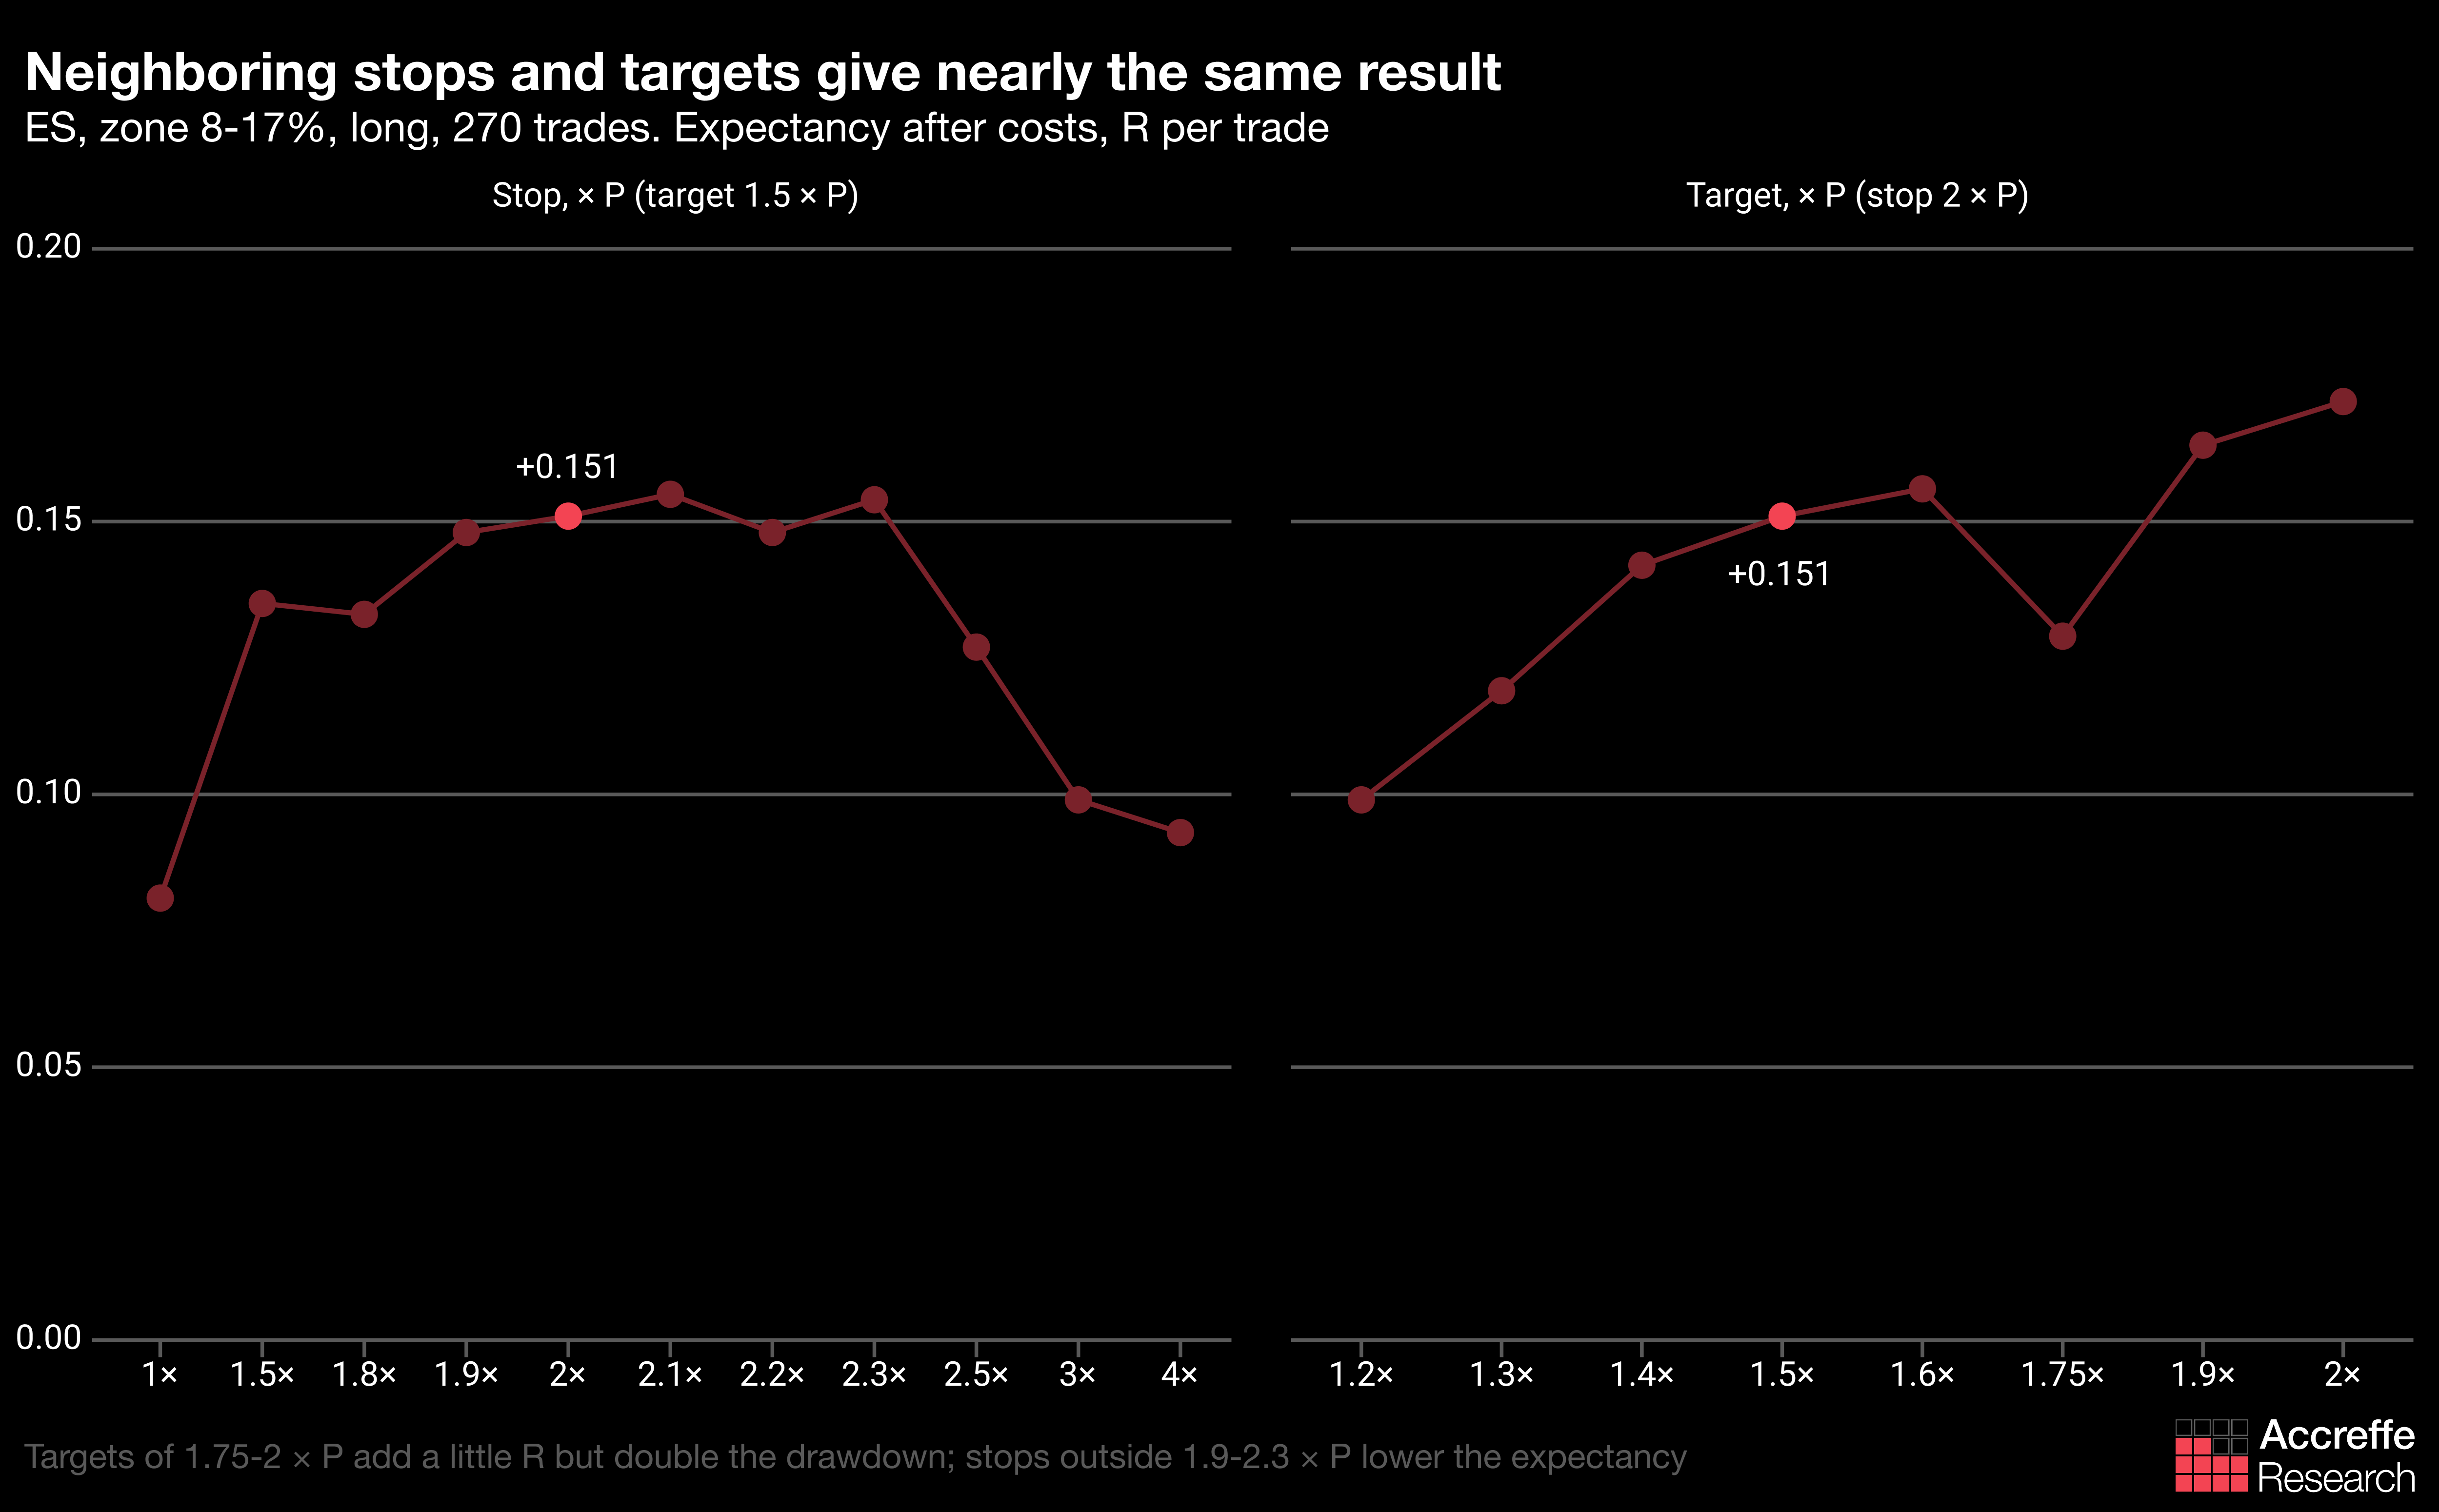
Stops from 1.9 to 2.3 × P and targets from 1.4 to 1.6 × P give EV within ±0.01R of the chosen one, less than the standard error (0.047R). The skew zone boundary is sensitive, though: with a 5-15% or 10-20% zone the gain is gone.
Doubling commission and all slippage cuts EV to +0.103R (t = 2.23), tripling them to +0.061R (t = 1.35). Entering on the close of minute 1, 2 or 5 instead of the open (same target and stop, measured from the open) gives +0.129R, +0.146R and +0.159R; days when a level fired before the entry are skipped (26, 47 and 101 days). The median target is 23 ticks, so the trade is sensitive to the fill at the open: every extra tick of slippage costs about 0.03R.
Other markets
I ran the strictest test on other markets. I took the same rules, didn’t touch a thing, and ran them on three other CME index futures. They weren’t part of the search, so I couldn’t have fitted anything to them. If the effect is real, it should show up here at least somewhat.
For each market: trades, win rate, profit factor, EV with its t-statistic, where a $100,000 account ended up at 1% risk, max drawdown and profitable years.
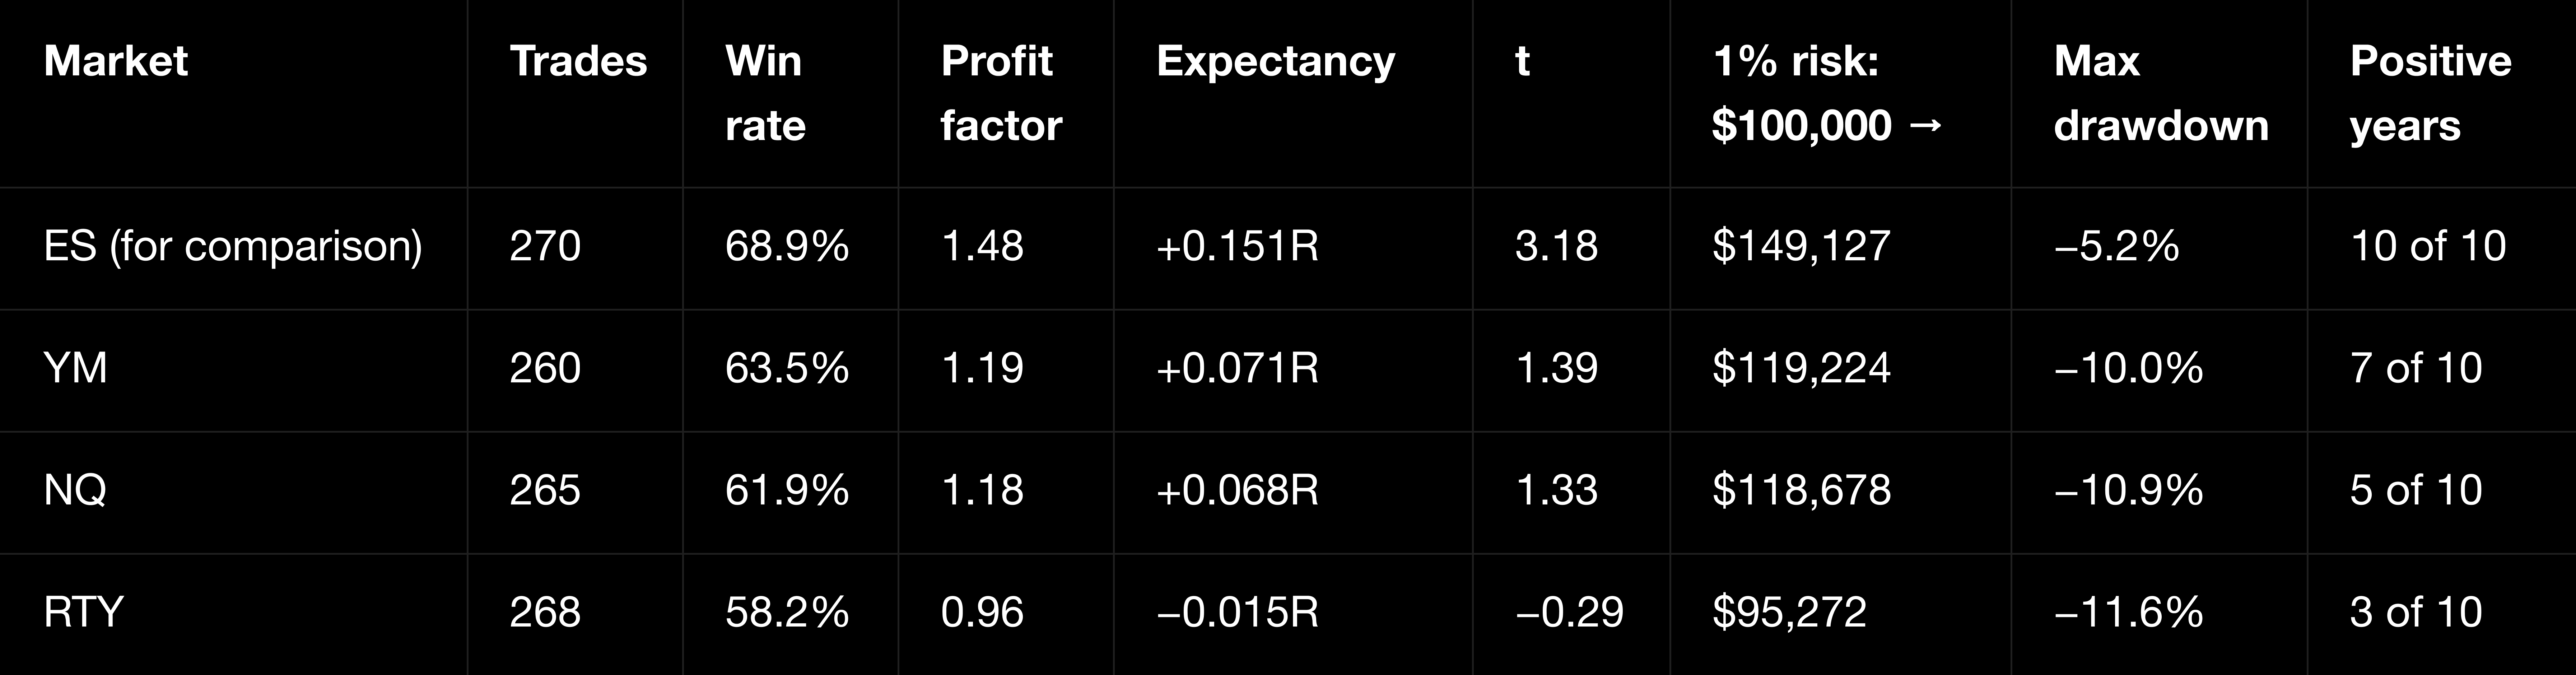
NQ and YM came out slightly green, RTY flat. The geometry’s the same everywhere: the near boundary comes first on 76.2-77.6% of days against a model value of 75.4-76.6%. Touches on their own don’t give an edge in any market.
I wouldn’t count the NQ and YM gain as confirmation either. Index futures move together: 45% of NQ trades and 41% of YM trades fall on days when ES had a signal too, and their results correlate with ES at 0.50 and 0.42. Without those days, NQ, YM and RTY together are left with 478 trades at −0.022R (t = −0.58). The rule works on the other indices exactly when it works on ES, so you can’t call this an independent test.
The peak around 10-15% also only shows up on ES. YM has a weak positive in 8-15%, the rest show no stable pattern. I checked whether a search on NQ and YM would find something of its own: 640 variants turned up 13 and 11 with t > 2. But if you shuffle overnight levels between days and break the link on purpose (200 permutations), you still find 4 and 3 such variants on average (p = 0.06 and 0.08), and a variant at least as good as the best real one turns up in 15% and 10% of permutations.
A separate word on NQ. Within the same 8-17% zone, the search found a ratio of its own there, target 1.2 × P and stop 1 × P: 265 trades, +0.185R (t = 2.85), 9 green years out of 10, and positive even on days without an ES signal (+0.21R, t = 2.44). Together with ES at 1% risk per trade, that would have made $215,739 with a −6.4% drawdown and a Sharpe of 1.37. But on ES and YM the same ratio gives +0.017R and −0.050R.
Why I should win against the other side
Before commissions, futures are a zero-sum game. If I’m making +0.151R per trade, someone’s losing that money. The question is who, and why.
One day, step by step
Here’s a typical day. The numbers are made up, but the proportions match the median trade. OVN High 7750.00, OVN Low 7716.75, open at 9:30 at 7746.00. The high is 4 points away (P = 16 ticks), skew 88/12. The target sits at 7752.00, 2 points above OVN High. The stop’s at 7738.00.
At 9:30 I buy at the market at 7746. Two kinds of traders usually sit on the other side at that moment. The first see 7750 as resistance and sell off the level. The second wait for price to clear 7750 and only buy after that, at 7750.25-7751. My limit sell sits at 7752. If the breakout happens, I hand my position to the ones who bought after confirmation, 6 points above where I bought. If it doesn’t, the stop at 7738 takes 8 points. It’s usually settled fast: median time in the trade is 9 minutes.
Whoever trades against me on these days loses on average. My trade makes +0.151R over 270 trades, while the mirror short at the open on the same days, with the same size target and stop, gives −0.198R (t = −3.84). ES rising over the period doesn’t explain it: the same long on all other days gives −0.035R over 1,992 trades, and with OVN High closer but outside the 8-17% zone, −0.050R over 954.
Where the edge is
The early entry on its own doesn’t give anything, though. Anyone can get in earlier. If price moved at random, a 6-point target above would hit before an 8-point stop below 57% of the time (8 / 14), and the early entry would make zero before costs. On ES in this zone the target hits first on 68.9% of trades, the stop on 30.7%, and another 0.4% close at 16:00.
The extra 12 percentage points of breakouts are the edge. The early entry lets me collect them, and they’re paid for by the ones who sold the level and the ones who bought after the breakout.
How much of those 12 points is real is a separate question. I found the 8-17% zone by searching, and the walk-forward keeps about half the EV, +0.07-0.10R per trade. If the excess breakouts shrink the same way, about 6 points above chance are left.
What to expect and where it’s weak
Forecast
Going forward I expect about half the backtest, +0.07-0.10R per trade. That’s roughly what the walk-forward gave.
To put that in dollars, I ran a 4-year Monte Carlo: 20,000 scenarios built from random trading days in 2017-2026, with some wins swapped for losses so that EV halves. At 1% risk the median by October 2030 is $109,000. The 10th and 90th percentiles are $97,000 and $121,000, and the chance of ending below the start is about 17%.
There are about 29 trades a year, and 30 trades won’t tell +0.07R apart from zero.
Where this backtest could be lying
Noise is the size of the effect. 270 trades give a standard error of EV of about 0.047R, roughly the gap between the backtest and the walk-forward.
Target fills. The target counts as filled on a touch of the level, with no limit order queue, and that overstates the result. The order of target and stop within a minute is unknown, though it never came up for this trade.
Slippage. 0.5 ticks at 9:30 may not be enough on news days, and with a 23-tick median target every extra tick costs about 0.03R.
Position size. Rounding to whole contracts isn’t modeled, so on a small account real risk will differ from 1%.
Market regime. 2017-2026 was mostly a rising market, and how the rule behaves in a long bear market is unknown.
2024-2026 made about 1.7% a year, and the current drawdown is the longest yet. That could be ordinary fluctuation, or it could be the effect fading, which is what I talked about at the start of the piece.
Bottom line
Over 2,262 ES days the near overnight boundary is touched first 73.1% of the time, and that’s geometry: the probability is set by skew and matches a random walk (p = 0.63), and half the touches come in the first 30 minutes. That’s why the symmetric trade toward the near boundary makes zero.
In the backtest, the asymmetric trade in the 8-17% zone below the overnight high made +0.151R per trade after costs, 10 profitable years out of 10 and a 5.2% drawdown at 1% risk. The gain doesn’t come from the early entry but from the extra breakouts: the target hits first on 68.9% of trades against 57% with a random price. The result holds up with other targets, stops, costs and entry delays, and the placebos lose money.
Adjusted for the search, the picture is more modest. The walk-forward keeps about half, DSR doesn’t confirm significance, and other markets don’t give independent confirmation.
I’ve shown 90 percent of the strategy, from finding the idea to possibly making money with it. What’s not here is deeper market data that could improve or worsen the strategy’s numbers: I left that work for you on purpose, so do it yourself.
I’d also recommend keeping in mind the problems you may run into. As I said, the strategy assumes ideal conditions, but in reality you’ll run into problems getting filled, at the very least from sitting in the limit order queue, as well as slippage. You’ll have to solve these problems on your own, as far as that’s possible.
Good luck.
I find research like this even more interesting for the thought process behind it than for finding a ready-to-use strategy. What I especially appreciate is seeing how you approach questions, develop hypotheses, and then try to prove yourselves wrong. After reading pieces like this, I often find myself looking at the market differently and asking questions that wouldn't have even crossed my mind before.
That's exactly why I enjoy both your work and Zeph's so much — it's a chance to see the market from a different angle and learn from the way you think about it. Thanks for sharing!
I also wanted to give a special mention to the visuals in your posts. The charts, graphics, and overall presentation just keep getting better. It's really noticeable and makes the research even more enjoyable to read!
Brutally honest, the stat about published strategies losing ~60% of their edge because the crowd devours them is why most public alphas are useless garbage.
But handing over the 83/17-92/8 asymmetry framework + leaving the execution grit and L2 optimization to the reader? That’s fair play. The real test isn't the backtest; it's surviving the fill quality and execution drift across those 29 trades a year.
Count me in for the dataset. Time to see if we can patch up that missing 10% without blowing it on slippage))
Like.